


Why Is Resolve First Financial Calling You — And Should You Be Worried?
If you're wondering why is resolve first financial calling me, here is the short answer:
- It may be a debt collector pursuing an old or disputed debt — but the calls often lack any real account details
- It may be a scam using the "Resolve First Financial" name to pressure you into calling back and handing over personal information
- It may be a case of mistaken identity — collectors sometimes use public records to target people with similar names to an actual debtor
- The calls are widely flagged on the BBB Scam Tracker with reports from Massachusetts, Colorado, Alabama, and other states as of late 2025 and early 2026
The safest default: do not call back the number shown on your caller ID until you have verified the caller independently.
Here is what makes these calls stand out from normal debt collection. The voicemails are deliberately vague. A typical message sounds something like this:
"This is a very important and time-sensitive call from Resolve First Financial. Please call the number shown on your caller ID to be connected with a live representative handling your account."
No name. No account number. No amount owed. No original creditor mentioned. That pattern alone is a major red flag — and it is exactly what scammers use to cast a wide net and see who calls back.
One BBB reporter lost $1,800 to a nearly identical scam targeting a debt that had been paid off for over 20 years. Others on Reddit's r/CRedit forum report receiving three to four calls per day from rotating phone numbers, about debts allegedly dating back to 2010 — debts that do not appear on any credit report.
This guide breaks down exactly what is going on, what your rights are, and how to protect yourself.
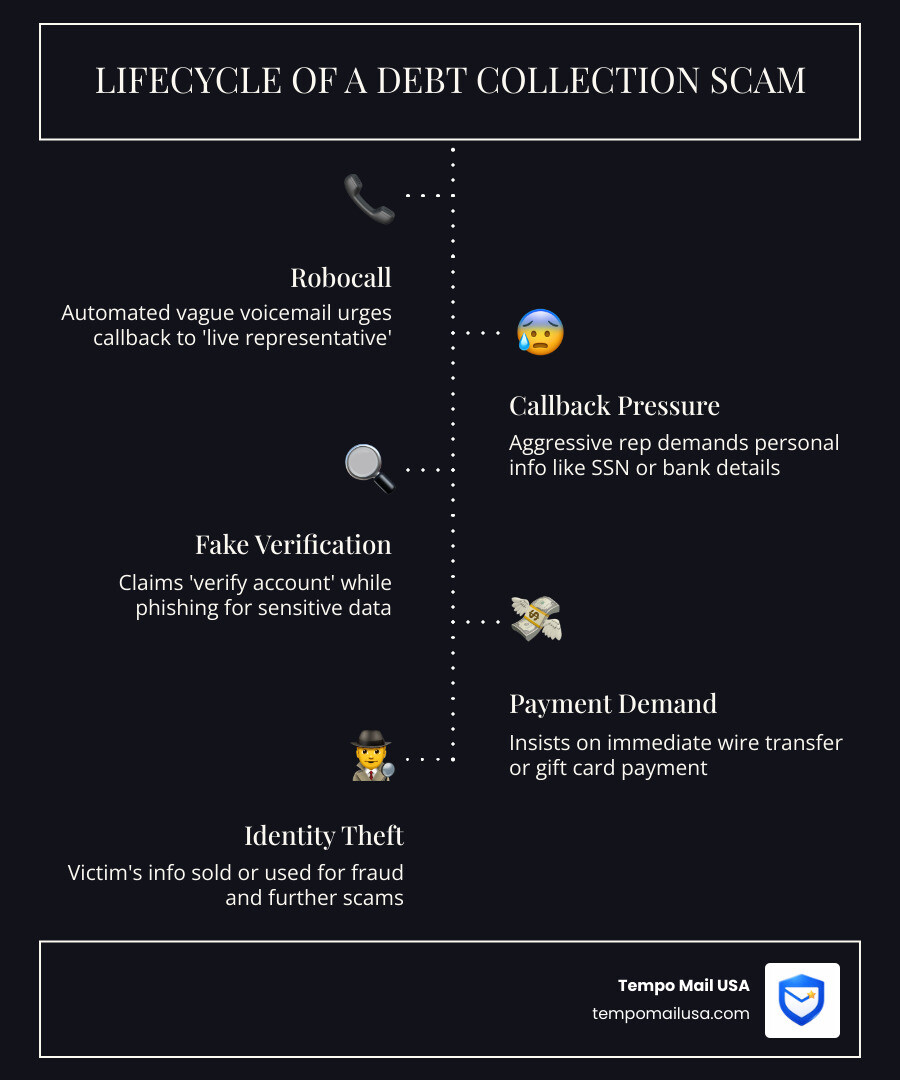
Why Is Resolve First Financial Calling Me?
When your phone lights up with a call from "Resolve First Financial," your first instinct might be panic. You might wonder if you forgot a credit card payment or if an old medical bill has finally caught up with you. However, the reality of why is resolve first financial calling me is often more complex than a simple missed bill.
According to research from Is Resolve First Financial a Scam?, this entity is frequently associated with aggressive debt collection tactics. While there are legitimate companies with similar names, the specific operation currently targeting consumers often operates in a "gray area" of the law. They use automated robocalls to reach thousands of people daily, hoping to find someone who is easily intimidated.
Decoding the "Why Is Resolve First Financial Calling Me" Voicemail
The voicemails left by this group are a masterclass in psychological pressure. They use "time-sensitive" language to create a false sense of urgency. By telling you to speak with a "live representative" immediately, they hope to bypass your logical defenses.
These generic scripts are a major warning sign. Legitimate debt collectors are required to provide specific information. If the voicemail doesn't mention your name or a specific account number, it’s likely a "blind" script. They are fishing for information, and by calling back, you are confirming that your phone number is active and that you are willing to engage.
Is the "Why Is Resolve First Financial Calling Me" Pattern a Scam?
The BBB Scam Tracker has been flooded with reports regarding these calls. Common complaints include predatory tactics and a total lack of debt specifics. In many cases, these calls are a front for phishing. The caller may already have some of your PII (Personally Identifiable Information), such as the last four digits of your Social Security number, which they use to build fake credibility.
As noted in Scams Details, many victims report that the callers become hostile when asked for written verification. This behavior is a hallmark of a scam. A real agency knows the law requires them to provide proof; a scammer only wants your credit card number.
Common Red Flags and Aggressive Tactics in 2026
As we move through May 2026, the tactics used by these callers have become increasingly sophisticated. One of the most common methods is "neighbor spoofing." This is when a caller manipulates the caller ID to display a local area code, making it more likely that you will pick up.
Specific numbers reported by consumers include:
- 508-683-0636 (Massachusetts)
- 617-404-1916 (Boston area)
- 571-302-8632 (Virginia)
Many users now rely on advanced security tools and VPN protection to prevent these attacks. Tools like NordVPN can help shield your digital footprint, making it harder for data brokers to link your IP address and location to your phone number. You can also learn more about similar patterns in our guide on Halsted Financial text scams.
Identifying "Zombie Debt" Harassment
"Zombie debt" is a term for old debts that are past the statute of limitations, have been discharged in bankruptcy, or were paid off years ago. Resolve First Financial has been linked to pursuing these "dead" accounts. For instance, users on Reddit have reported being hounded for HSBC debts from as far back as 2010.
If you are being contacted for a debt you already settled, you aren't alone. A Complaint / Review: Resolve 1st Financial highlights a case where a consumer was harassed for a debt that had a satisfied judgment on public record. These collectors often buy "junk" debt portfolios for pennies on the dollar and hope to scare you into paying something—anything—even if you don't legally owe it.
Illegal Threats and Intimidation
One of the most frightening tactics used by these callers is the threat of legal action or arrest. It is crucial to remember: Debt is a civil matter, not a criminal one.
Under the Fair Debt Collection Practices Act (FDCPA), it is illegal for a collector to:
- Threaten you with jail or arrest.
- Claim they are government officials or attorneys (if they aren't).
- Threaten to garnish your wages without a court order.
If you hear these threats, you are likely dealing with a fraudulent operation. For more details on spotting these criminals, check out our article on warning signs of fake debt collectors.
Your Legal Rights and Debt Verification Steps
Knowing your rights is your best defense against financial harassment. The FDCPA provides a clear framework for how collectors must behave.
| Feature | Legitimate Collector | Fraudulent Caller |
|---|---|---|
| Written Notice | Must send within 5 days of contact | Refuses to send anything in writing |
| Debt Details | Provides original creditor and amount | Uses vague terms like "your account" |
| Payment Method | Check, credit card, or bank portal | Requests gift cards or wire transfers |
| Tone | Professional (usually) | Threatening or overly urgent |
According to Scams Details, fraudulent callers will often hang up the moment you mention your legal right to a validation notice.
How to Demand a Validation Notice
If you are unsure why is resolve first financial calling me, the first step is to demand a validation notice. By law, they must provide this within five days of their initial contact.
We recommend sending a formal request via certified mail with a return receipt requested. This creates a paper trail that can be used if you need to file a lawsuit or a complaint with the CFPB. For a comparison of how legitimate agencies handle this, see our Halsted Financial legitimacy check.
Checking Your Credit Report for Real Debts
Before you even think about paying a cent, verify the debt exists. Go to AnnualCreditReport.com and pull your reports from Experian, Equifax, and TransUnion. If the debt isn't there, or if it shows as "paid," the caller is likely trying to scam you.
Sometimes, "zombie debt" collectors use secondary bureaus like LexisNexis to find your information. Reports on Scams Details suggest that these callers use old addresses and outdated phone numbers to find "matches" for people who might share your name but aren't actually the debtor.
How to Stop the Calls and Protect Your Identity
Stopping the harassment requires a proactive approach. The most effective way to end the calls is to send a "Cease and Desist" letter. Once a collector receives this, they are legally barred from contacting you again, except to notify you of a specific legal action (like a lawsuit).
You should also:
- Register for the National Do Not Call Registry: While this doesn't stop all scammers, it helps filter out some legitimate telemarketers.
- Silence Unknown Callers: Use your smartphone's built-in settings to send any number not in your contacts directly to voicemail.
- Use Call Filtering Apps: Many mobile carriers offer free or paid apps that flag "Potential Spam."
Protecting your digital identity is just as important as blocking numbers. Vulnerable populations are often targeted, as seen in our resources on elder financial abuse protection. Additionally, using a VPN like NordVPN helps prevent your data from being scraped by the very brokers who sell "lead lists" to these callers.
Reporting Suspicious Activity to Authorities
Don't just block the number—report it. This helps authorities build a case against these operations.
- FTC: Report at ReportFraud.ftc.gov.
- CFPB: Submit a complaint if a collector is violating the FDCPA.
- State Attorney General: Most states have a consumer protection division that investigates debt collection scams.
If you are concerned about a loved one in a care facility, you can also look into nursing home financial abuse resources.
What to Do if You Already Shared Information
If you've already spoken to a representative from Resolve First Financial and shared your Social Security number or bank details, you must act fast:
- Place a Fraud Alert: Contact one of the three major credit bureaus to place a one-year fraud alert.
- Freeze Your Credit: This is the most effective way to prevent new accounts from being opened in your name.
- Update Passwords: Change the passwords for your banking and email accounts.
Be especially wary of follow-up calls from entities claiming to be "legal compliance" departments, as these are often part of the same scam. See our Department of Legal Compliance scam warnings for more info.
Best Tools to Protect Yourself from Financial Harassment (Compared)
In 2026, the best defense is a "PII Firewall" strategy. This means limiting the amount of real personal data you share online.
- Identity Theft Protection Services: Services like Aura or LifeLock monitor your SSN and credit in real-time.
- Call Filtering Apps: Apps like Hiya or RoboKiller use massive databases to block known scam numbers.
- VPN Privacy Protection: NordVPN masks your IP address and encrypts your data, preventing trackers from building a profile on you.
- Temporary Email Aliases: Using Tempo Mail USA allows you to sign up for services without giving away your primary email address, which is often used by scammers to find your phone number and other PII.
How to Choose the Right Privacy Solution
When choosing a solution, look for tools that offer data breach monitoring. If your data was leaked in a breach (which is likely how these callers got your info), you need to know exactly what was exposed.
As discussed in this Potential Scam? Reddit Discussion, many victims found that their information was sourced from old public records. By using temporary aliases and identity proxying, you can stop the flow of your data to these "sucker lists."
Frequently Asked Questions about Resolve First Financial
Is Resolve First Financial a legitimate company?
While some entities with similar names exist in the financial sector, the 2026 calls from numbers like (571) 302-8632 are widely flagged as scams. These callers use aggressive, illegal tactics, refuse to provide written validation, and often target "zombie debts" that are no longer legally collectible.
Can a debt collector threaten me with arrest?
No. Under the Fair Debt Collection Practices Act (FDCPA), debt is strictly a civil matter. It is a federal crime for a debt collector to threaten you with arrest, jail time, or any criminal penalty to coerce payment.
How did they get my Social Security number and date of birth?
Scammers rarely "hack" you directly. Instead, they purchase "lead lists" from the dark web or shady data brokers. These lists are compiled from past data breaches, public records, and social media scraping. They use this information to establish false credibility and trick you into believing they are a legitimate financial institution.
Conclusion
The question of why is resolve first financial calling me usually points toward a predatory or fraudulent operation. Whether they are a "bottom-feeding" debt collector or an outright scammer, your response should be the same: Verify everything, share nothing, and demand proof in writing.
In an age where our personal information is constantly for sale, maintaining digital hygiene is essential. By using a "PII Firewall" strategy—including tools like NordVPN and temporary email aliases—you can protect your identity from being exploited.
Protect your data and stop the cycle of harassment at TempoMailUSA.com. By shielding your real contact information, you can ensure that the next time a scammer tries to call, they won't even have your number.