


Why Comparing Investment App Fees and Risk Really Matters
Best Investment Apps Portfolio Management Fees and Risk Comparison is one of the most important things you can do before putting a single dollar into any platform — because fees compound just as fast as returns do.
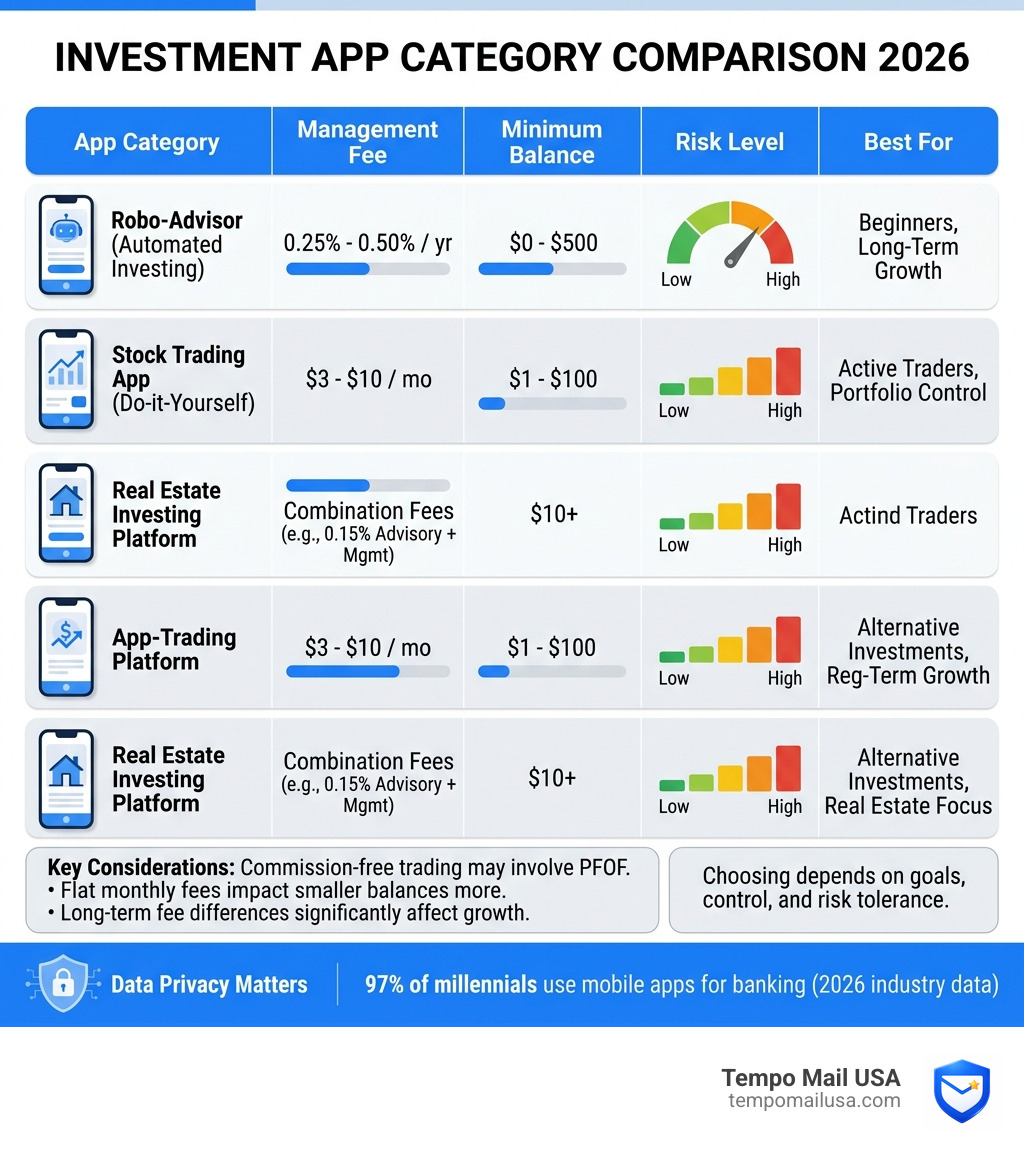
Here's a quick breakdown of the top apps by fee structure and risk profile:
| App | Management Fee | Minimum Balance | Risk Level | Best For |
|---|---|---|---|---|
| Fidelity Go | 0% (under $25K), 0.35% (above) | $0 | Low-Medium | All-in-one beginners |
| Betterment | 0.25%/yr ($4/mo under $20K) | $0 | Low-Medium | Automated investing |
| Wealthfront | 0.25%/yr | $500 | Low-Medium | Tax optimization |
| Robinhood | $0 (Gold: $5/mo) | $0 | Medium-High | Active traders |
| Acorns | $3–$12/mo | $5 | Low | Micro-investors |
| M1 Finance | $3/mo (waivable) | $100 | Medium | Custom portfolios |
| Charles Schwab | $0 | $0 | Low-High | Beginners + research |
| Webull | $0 (SmartAdvisor: 0.20%/yr) | $5 | Medium-High | Active + paper trading |
| Fundrise | 0.15% advisory + 0.85% mgmt | $10 | Medium-High | Real estate investing |
A few things to know right now:
- Commission-free doesn't mean truly free. Many apps earn money through payment for order flow (PFOF), which can mean slightly worse trade execution prices for you.
- Flat monthly fees hurt small accounts most. Acorns' $3/month fee equals 3.6% annually on a $1,000 balance — far higher than any robo-advisor's percentage fee.
- A 0.50% fee difference on $100,000 over 30 years can cost you over $100,000 in lost growth.
The right app depends entirely on your goals, how much control you want, and how much risk you're comfortable with. No single app wins for everyone.
Choosing where to invest isn't just about returns. It's about what you give up to get there — in fees, in risk, and increasingly, in personal data. When you sign up for a brokerage or investment app, you're sharing your Social Security number, bank account details, and financial history. For privacy-conscious investors, that's a real concern worth weighing alongside management fees and portfolio performance.
According to industry data, 89% of people now use mobile apps for banking, with that number hitting 97% among millennials. The flood of investment apps competing for your attention means more choices — but also more complexity, more hidden costs, and more potential exposure of your personal information.
This guide cuts through the noise.
Best Investment Apps Portfolio Management Fees and Risk Comparison
When we look at the landscape in 2026, we see a clear divide between "do-it-for-me" robo-advisors and "do-it-yourself" trading platforms. Each carries a different price tag and a unique risk profile.
Robo-Advisors: The Cost of Automation
Robo-advisors like Betterment and Wealthfront have revolutionized portfolio management by using algorithms to manage diversified ETF portfolios. Their standard fee of 0.25% annually is significantly lower than the 1% or more typically charged by traditional human advisors.
However, we must watch the fine print. Betterment, for instance, charges a flat $4 monthly fee if your balance is under $20,000 and you don't set up a $200 monthly deposit. For a small $1,000 account, that $48 a year represents a staggering 4.8% fee—effectively wiping out most of your expected market gains.
Full-Service Brokerages: Zero Fees, High Value
Legacy giants like Fidelity and Charles Schwab have adapted to the mobile era with incredible success. Fidelity Go offers 0% management fees for balances under $25,000, making it a "best-in-class" option for those starting their journey. Schwab also offers $0 commissions on stocks and ETFs, and they provide some of the best research tools in the industry. For a deeper dive into these rankings, we recommend checking out Best Investing Apps in 2026 — A Clear-Eyed Comparison .
The Risk of Expense Ratios
Beyond the platform fee, we have to consider the expense ratio of the funds themselves. A passive S&P 500 index fund might charge as little as 0.03%, while an actively managed fund could charge 0.75%. Over 30 years, that small gap can lead to a six-figure difference in your final net worth.
Evaluating Hidden Costs and Financial Recovery Risks
The term "commission-free" is the greatest marketing achievement of the last decade, but it doesn't mean "cost-free." We need to be vigilant about the secondary ways these apps generate revenue, as some can lead to significant financial leakage.
Payment for Order Flow (PFOF)
Apps like Robinhood and Webull often use PFOF. This means they send your trade requests to market makers who pay the app a small fee to execute the trade. The risk here is that you might not get the absolute best price available on the market. While the difference might only be a few cents per share, it adds up for active traders. Public is one of the few apps that took a principled stand by eliminating PFOF to prioritize trade transparency.
The "Inactivity" and "Withdrawal" Trap
Some apps charge you for not using them. Inactivity fees can quietly drain a dormant account. Others might charge $75 or more to transfer your assets to a different brokerage (ACAT fee). We also see currency conversion fees in international-facing apps like Revolut or Trade Republic, which can take a 0.5% to 1.5% bite out of every cross-border trade. For more on these "gotchas," read Monarch Investment Fees Hidden Costs Exposed.
Fraud and Recovery
If you fall victim to a scam or unauthorized access, the path to recovery is steep. While SIPC protects you if the brokerage fails, it does not protect you if you are tricked into sending money to a scammer. If you find yourself in this position, consulting an Investment Fraud Lawyer Recover Your Money may be your only recourse to navigate the complex legal landscape of financial recovery.
Best Investment Apps Portfolio Management Fees and Risk Comparison for Retirement
Retirement planning in 2026 has become highly competitive, with apps offering aggressive incentives to capture your long-term capital.
- IRA Matching: Robinhood Gold offers a 3% match on IRA contributions. On a maximum $7,500 contribution (the 2026 limit for those under 50), that is an "instant" $225 return. Webull and Public have launched similar matching programs.
- Tax-Advantage Efficiency: Robo-advisors excel here by automating tax-loss harvesting. This involves selling losing investments to offset capital gains taxes, which can add 0.5% to 1.5% to your annual after-tax returns.
- Diversification via REITs: Many investors are using apps like Fundrise to add real estate to their IRAs. This provides a hedge against stock market volatility. To understand how to keep more of those gains, see Reit Tax Benefits And Income Strategy Pay Less Tax.
Security Protocols and Identity Theft Protection in Modern Brokerages
As we operate in the privacy and cybersecurity industry, we cannot emphasize enough that your financial security is only as strong as your weakest login.
Most top-tier apps now offer SIPC insurance, which covers up to $500,000 in securities (including $250,000 in cash) if the firm goes bust. However, this is not a shield against market losses or identity theft. We always look for apps that offer:
- Multi-Factor Authentication (MFA): Ideally via an authenticator app, not just SMS.
- Biometric Encryption: Using your face or fingerprint to authorize trades.
- Account Segregation: Keeping client funds separate from company operating capital.
We must also stay alert for sophisticated phishing. Scammers often spoof reputable names to steal credentials. For example, recent alerts like the Janus Henderson Scam Fca Fine Fake Investment Fraud and the Pwc Scam Alert Fake Emails Jobs Investment Fraud highlight how criminals use the "halo effect" of big brands to trick investors into revealing PII (Personally Identifiable Information).
Best Investment Apps Portfolio Management Fees and Risk Comparison for Small Portfolios
If you are starting with under $1,000, your biggest "risk" isn't the market—it's the fee-to-balance ratio.
- Fractional Shares: Apps like Charles Schwab (Stock Slices), Fidelity, and Robinhood allow you to buy $1 or $5 worth of a stock that might trade for $500. This is vital for diversification in small portfolios. Without fractional shares, you might be forced to put 50% of your money into one company just to own a single share.
- Micro-Investing: Acorns and Stash popularized the "round-up" model, where your spare change is invested. While excellent for building habits, we must reiterate: watch the monthly fees. A $3 monthly fee on a $100 balance is a 36% annual fee. If you have a low balance, look for percentage-based apps like Fidelity Go or Wealthfront instead. For a broader list of entry-level options, see The 8 Best Investment Apps of 2026 .
Advanced Risk Management: Automation vs. Manual Control
For the more seasoned investor, portfolio management is about metrics like the Sharpe Ratio (which measures risk-adjusted return) and Volatility.
The Case for Automation
Robo-advisors provide automated rebalancing. If your goal is 60% stocks and 40% bonds, and stocks have a great month, your portfolio might shift to 70/30. The app will automatically sell some stocks and buy bonds to bring you back to your risk target. Doing this manually is tedious and often leads to emotional mistakes (like "letting it ride" until the crash).
Hybrid Customization
M1 Finance offers a unique "Pie" system. You choose your assets (up to 100), and the app automatically directs your future deposits to the "slices" that are currently underweight. This gives you the control of a brokerage with the automation of a robo-advisor.
Professional Research Tools
If you prefer manual control, you need data. Platforms like Stock Rover and Morningstar Investor provide professional-grade analytics. Morningstar's "X-Ray" tool is particularly useful for seeing if you are accidentally over-exposed to a single sector across multiple ETFs. You can find more details on these tools in the guide to Best Portfolio Management Tools for 2026: Top Picks & Features .
Frequently Asked Questions about Investment App Security
How do I recover money from an unauthorized bank transaction in 2026?
If you spot an unauthorized transaction, time is your enemy. You should immediately:
- Freeze your investment and bank accounts.
- File a report with the brokerage's fraud department.
- Contact the FTC at IdentityTheft.gov.
- If it was a wire transfer, contact the sending and receiving banks immediately to initiate a "kill chain" request. Recovery is difficult, so prevention via secure aliases is always better than a cure.
Are commission-free apps safe from identity theft and data breaches?
No app is 100% safe. While they use high-level encryption, they are prime targets for hackers because they hold both money and sensitive PII. In 2026, we've seen that even the biggest names can have vulnerabilities. The best way to stay safe is to limit the amount of real data you share. Using a temporary email for the initial sign-up and "newsletters" can prevent your primary inbox from being targeted by phishing attacks.
What is the best way to dispute wire transfer fraud on a trading platform?
Wire transfers are generally considered "same as cash," making them incredibly hard to reverse. To dispute one, you must act within hours. You will need a police report and a formal letter of dispute sent to your bank's fraud department. Be wary of "recovery specialists" on social media who claim they can hack the blockchain or bank systems to get your money back—these are almost always secondary scams.
Conclusion
The Best Investment Apps Portfolio Management Fees and Risk Comparison shows us that the "best" app isn't the one with the flashiest interface, but the one that aligns with your financial goals while protecting your bottom line and your privacy.
At Tempo Mail USA, we understand that your digital footprint is your biggest vulnerability. When you're researching these apps, signing up for newsletters, or testing out new platforms, you're often forced to hand over your primary email address—the key to your entire digital life. Our secure alias generation acts as a firewall, protecting your real identity from data breaches and intrusive marketing.
In 2026, investing isn't just about picking the right stocks; it's about picking the right defenses. Protect your portfolio from high fees, and protect your identity with tempomailusa.com.