


Why Real Estate Investment Trust Tax Benefits and Income Strategy Matter for Income Investors
Real Estate Investment Trust Tax Benefits and Income Strategy is one of the most compelling — and misunderstood — areas of personal finance. For investors looking to execute this strategy, opening a dedicated high-yield brokerage account is the primary commercial gateway to accessing these institutional-grade assets. REITs offer individual investors a rare combination of high dividend income, corporate tax avoidance, and powerful tax deferral mechanisms that most other asset classes simply cannot match.
Here is a quick breakdown of the core tax benefits REITs offer:
- No corporate-level tax — REITs avoid federal corporate income tax by distributing at least 90% of their taxable income to shareholders
- 20% QBI deduction (Section 199A) — Individual investors can deduct 20% of qualified REIT dividends, reducing the effective top federal rate from 37% to 29.6%
- Return of Capital (ROC) — Depreciation allows 60–90% of REIT distributions to be classified as ROC, deferring taxes and potentially lowering your effective rate to as little as 3%
- Favorable capital gains rates — Long-term capital gains on REIT shares are taxed at 0%, 15%, or 20% depending on your income bracket
- Tax-advantaged account compatibility — Holding REITs in an IRA or 401(k) can defer or eliminate taxes on distributions entirely
REITs have quietly become one of the most tax-efficient income vehicles available to everyday investors. The structure is elegant: a REIT collects rent from commercial properties — offices, warehouses, apartments, healthcare facilities — and passes the bulk of that income directly to shareholders. Because it distributes rather than retains earnings, it sidesteps the corporate tax layer that eats into returns from most other equity investments.
Many users now rely on secure platforms, insurance coverage, and advanced privacy tools to avoid financial or data-related risks. When signing up for investment newsletters, REIT platforms, or financial research tools, privacy-conscious investors use services like Tempo Mail USA as a PII firewall to avoid spam overload and data exposure from routine financial sign-ups.
Understanding the Real Estate Investment Trust Tax Benefits and Income Strategy

To truly master a Real Estate Investment Trust Tax Benefits and Income Strategy, we first need to look at the unique legal "engine" that makes these trusts go. A REIT isn't just a company that likes real estate; it is a specific corporate designation created by Congress in 1960 to allow everyday people to invest in large-scale, income-producing real estate.
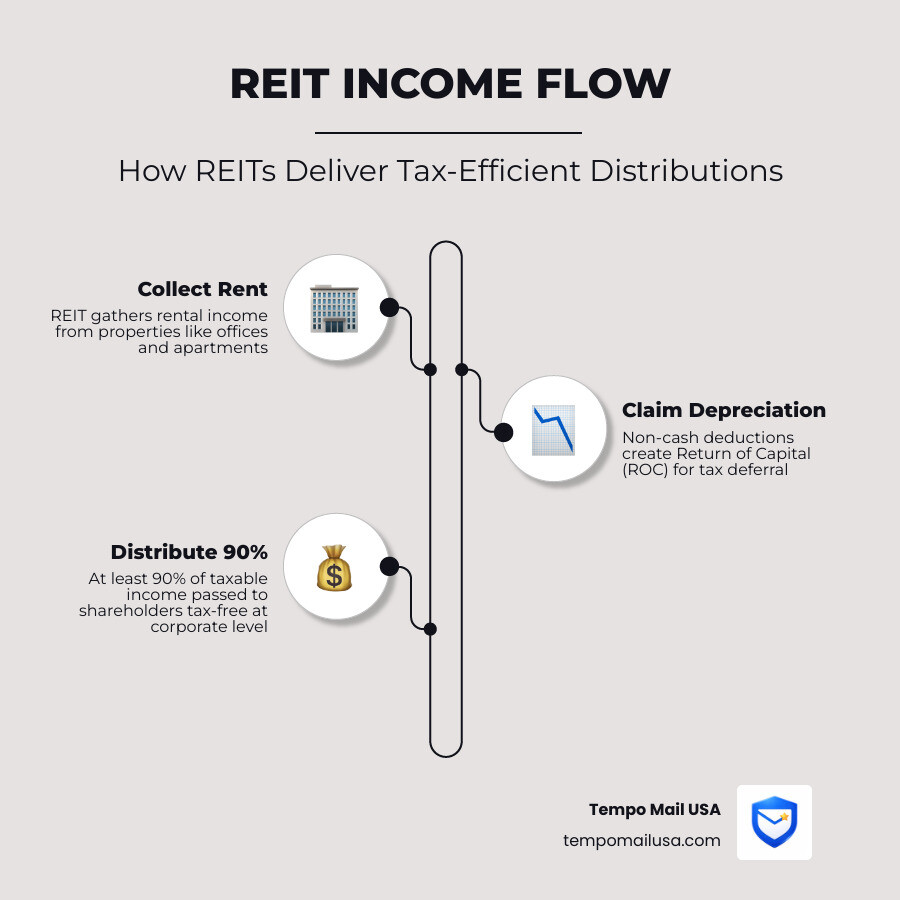
The magic word is "conduit." For tax purposes, a REIT acts as a pass-through entity. As long as the trust distributes at least 90% of its taxable income to its shareholders annually, it is permitted to deduct those dividends from its corporate taxable income. In practice, most REITs distribute 100% of their taxable income to completely eliminate their federal tax bill at the corporate level.
This creates a massive advantage over traditional corporations (C-Corps). When a standard company makes a profit, the IRS takes a cut at the corporate level (currently 21%), and then you pay personal income tax on whatever is left over when it's paid out as a dividend. With REITs, that first layer of "double taxation" is removed. Every dollar of rent collected (minus operating expenses) flows directly toward your pocket. You can learn more about how these distributions grow over time using a compound interest calculator.
According to Nareit, this structure is why REIT dividend yields have historically been significantly higher on average than other equities. It isn't just that real estate is a good business; it's that the tax code forces the company to give the money to you rather than keeping it or giving it to the government.
The Core Components of a Real Estate Investment Trust Tax Benefits and Income Strategy
When building your strategy, it is helpful to distinguish between the two primary flavors of REITs:
- Equity REITs: These are the most common. They own and operate physical properties—think malls, data centers, and apartment complexes. Their income comes primarily from rent. They offer excellent inflation protection because as the cost of living rises, landlords typically raise rents.
- Mortgage REITs (mREITs): Instead of owning buildings, these trusts provide financing for real estate by purchasing or originating mortgages and mortgage-backed securities. Their income comes from the "spread" between interest earned on mortgage loans and the cost of funding those loans.
Both types offer portfolio diversification because real estate often has a low correlation with the broader stock market. This means when tech stocks are sliding, your REIT holding might stay steady or even climb, providing a much-needed "smoothing" effect for your total wealth.
Maximizing After-Tax Yields with Section 199A
One of the most powerful modern tools for REIT investors is the Section 199A deduction, often referred to as the Qualified Business Income (QBI) deduction. Introduced by the Tax Cuts and Jobs Act and extended through 2025 (and potentially beyond under the "One Big Beautiful Bill Act" of recent years), this allows individual shareholders to deduct 20% of their "qualified" REIT dividends from their taxable income.
This is a game-changer for high-income earners. If you are in the top federal tax bracket of 37%, the 20% deduction effectively lowers your tax rate on those dividends to 29.6%. Unlike other QBI deductions, the REIT version generally does not have the same strict income or wage limitations, making it accessible to a much broader range of investors.
Decoding REIT Dividend Taxation: Ordinary Income vs. Return of Capital
When tax season rolls around, you won't just see one number for your REIT income. Instead, your Form 1099-DIV will break your distributions into different "buckets." Understanding these buckets is essential for an effective Real Estate Investment Trust Tax Benefits and Income Strategy.
| Distribution Type | Tax Treatment | 1099-DIV Box |
|---|---|---|
| Ordinary Income | Taxed at your marginal rate (minus 20% QBI deduction) | Box 1a |
| Capital Gains | Taxed at long-term rates (0%, 15%, or 20%) | Box 2a |
| Return of Capital (ROC) | Non-taxable; reduces your cost basis | Box 3 |
As noted in the Nuveen RealAccess report, the "Return of Capital" component is where the real tax magic happens.
How Return of Capital (ROC) Enhances Your Real Estate Investment Trust Tax Benefits and Income Strategy
In real estate, depreciation is a beautiful thing. It is a "non-cash" expense. Even if a building is actually increasing in market value, the IRS allows the owner to write off a portion of the building's cost every year as if it were wearing out.
REITs pass this benefit to you. Because depreciation reduces the REIT's taxable income but doesn't reduce the cash it has available to pay you, a portion of your check is often classified as a "Return of Capital."
Why this is great:
- Tax Deferral: You don't pay taxes on the ROC portion in the year you receive it.
- Cost Basis Adjustment: Instead of being taxed now, the ROC amount reduces your "cost basis" (what you paid for the stock).
- Example: If you bought a share for $100 and received $5 in ROC, your new basis is $95. You only pay tax on that $5 when you eventually sell the stock, and even then, it is usually at the lower long-term capital gains rate.
This allows for effective "income smoothing." You get the cash flow today to pay your bills, but you defer the tax bill for years or even decades.
Reporting and Compliance: Decoding Form 1099-DIV
Decoding your 1099-DIV is the final step in compliance. While most dividends from standard stocks are "qualified" (taxed at 15% or 20%), most REIT dividends are "non-qualified" and show up in Box 1a as ordinary dividends. However, don't panic—remember that 20% QBI deduction we discussed earlier!
REITs often use cost segregation studies to accelerate depreciation on certain parts of their properties (like HVAC systems or parking lots), which can increase the amount of ROC you receive in the early years of an investment. Most public REITs provide this data by late January or February, so keep an eye on your mailbox (or your secure digital portal).
Comparison: Taxable Accounts vs. Retirement Vehicles for REITs
Deciding where to hold your REITs is a critical decision-driven step in your Real Estate Investment Trust Tax Benefits and Income Strategy. The following comparison helps you choose the right "bucket" for your assets:
| Feature | Tax-Advantaged (IRA/401k) | Taxable Brokerage Account |
|---|---|---|
| Tax on Dividends | Deferred or Zero (Roth) | Taxed at Ordinary Rates (minus QBI) |
| ROC Benefit | Neutral (Tax-free anyway) | High (Defers taxes, lowers basis) |
| Liquidity | Restricted until age 59.5 | High (Withdraw anytime) |
| Best For | Long-term wealth compounding | Immediate cash flow needs |
If you are looking to finance a large purchase or manage debt while investing, a loan calculator can help you balance your cash flow needs. While Roth IRAs are the "Gold Standard" for tax-free growth, taxable accounts allow you to utilize tax-loss harvesting to offset gains. For high-net-worth investors, REITs also offer the Step-up in Basis tool; if you hold shares until death, heirs receive them at fair market value, effectively forgiving years of deferred tax debt from ROC distributions.
Risk Management and Compliance in REIT Investing
No Real Estate Investment Trust Tax Benefits and Income Strategy is complete without addressing risk. REITs are sensitive to interest rates; when rates go up, the cost of borrowing for the REIT increases, which can squeeze profit margins. Furthermore, REITs must follow strict IRS rules, such as the 75% Asset Test and the 5/50 Rule, to maintain their tax-exempt status.
When managing these investments online, it is vital to protect your financial footprint. Using NordVPN while accessing your brokerage account ensures your session is encrypted, protecting you from man-in-the-middle attacks and ensuring your sensitive financial data remains private. You can also use a mortgage calculator to see how interest rate shifts might affect the underlying property values in your REIT's portfolio.
One common mistake is failing to account for state taxes. Most states tax REIT dividends as ordinary income, and they don't all recognize the federal 20% QBI deduction. To protect your identity when signing up for new REIT research platforms, we recommend using Tempo Mail USA as a PII firewall. This creates a secure buffer, ensuring that if a research site is ever breached, hackers get a temporary alias rather than your real identity.
Frequently Asked Questions about REIT Taxation
1. How much of their income must REITs distribute to shareholders?
REITs are legally required to distribute at least 90% of their taxable income to shareholders annually to maintain their status as a pass-through entity and avoid federal corporate-level taxation.
2. Does the 20% QBI deduction apply to all REIT dividends?
Yes, under Section 199A, individual investors can generally deduct 20% of the "ordinary income" portion of their REIT dividends from their taxable income, regardless of whether they itemize deductions.
3. What is the tax impact of a Return of Capital (ROC) distribution?
Return of Capital is not taxed when you receive it; instead, it reduces your cost basis in the stock, which defers the tax liability until you sell the shares, at which point it is typically taxed at lower capital gains rates.
Conclusion
A well-executed Real Estate Investment Trust Tax Benefits and Income Strategy is one of the most effective ways to build long-term wealth. By combining high-yield dividends with corporate tax avoidance, the 20% QBI deduction, and the tax-deferral power of Return of Capital, you can keep significantly more of what you earn.
Whether you are holding equity REITs for inflation protection or mortgage REITs for aggressive income, the key is to stay informed and stay secure. Wealth preservation isn't just about picking the right stocks; it's about protecting your data and your identity while you grow your portfolio.
When signing up for new investment platforms or financial newsletters, savvy investors use Tempo Mail USA as a PII firewall to shield their real identity and protect against data exposure. Start building your tax-efficient real estate empire today—securely.