


Is Yrefy a Safe and Legitimate Investment? Here's What You Need to Know First
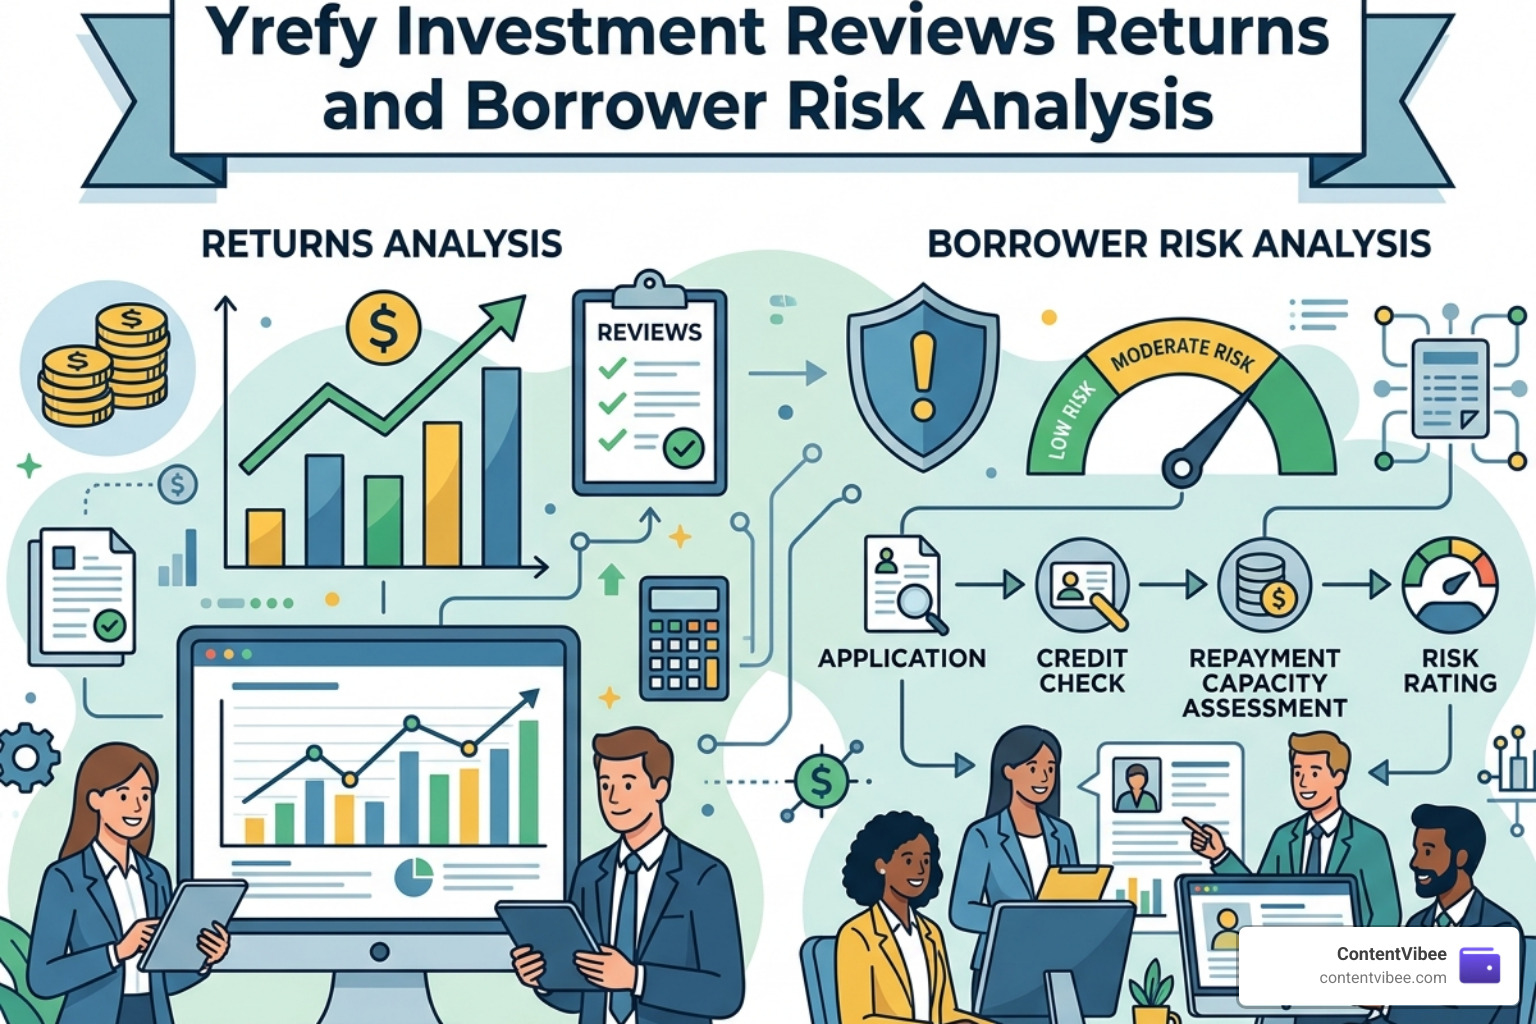
Yrefy Investment Reviews Returns and Borrower Risk Analysis is one of the most searched questions among accredited investors weighing this alternative fixed-income product against safer options.
Here is a quick snapshot before we go deeper:
| Factor | Yrefy at a Glance |
|---|---|
| Advertised return | Up to 10.25% (5-year term) |
| Minimum investment | $50,000 |
| Borrower type | Defaulted or delinquent private student loans |
| Claimed default rate | Less than 2% |
| Regulatory structure | Reg D 506(c) private placement |
| FDIC/SIPC insured | No |
| Key legal issue | $750,000 Massachusetts fine (Feb 2025) |
| Liquidity | Illiquid; 90-day early withdrawal processing |
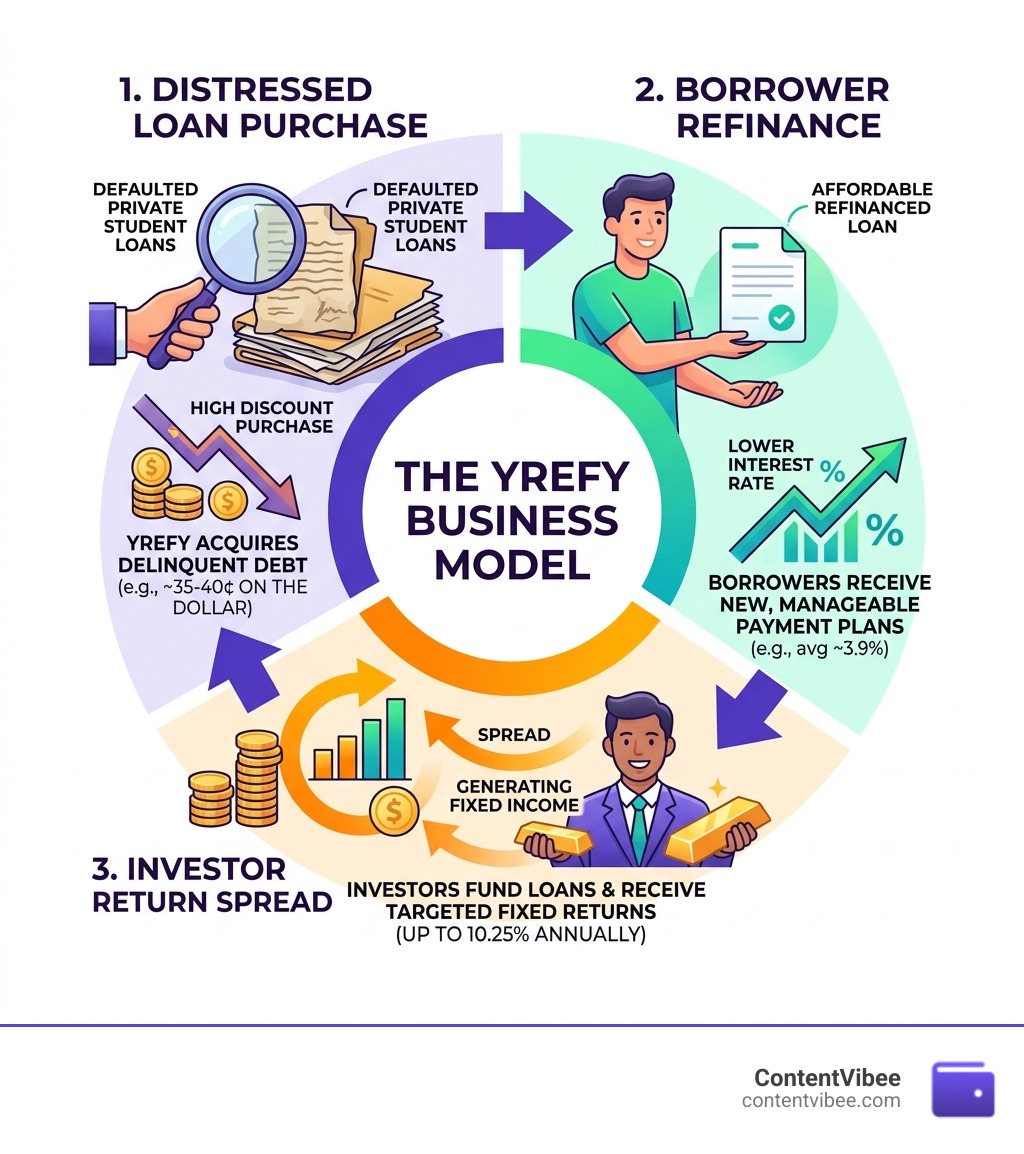
Yrefy has been operating since 2017. It buys distressed private student loans at roughly 35–40 cents on the dollar, then refinances them to struggling borrowers at an average 3.9% interest rate. Investors fund those loans and receive fixed returns up to 10.25% annually.
That spread sounds attractive. But the gap between what borrowers pay and what investors are promised is a central concern that critics — including a Massachusetts regulator — have flagged publicly.
If you are a self-directed investor trying to decide whether this belongs in your portfolio, this guide breaks down the real numbers, the verified risks, and what independent sources actually say.
Yrefy Investment Reviews Returns and Borrower Risk Analysis: An Overview
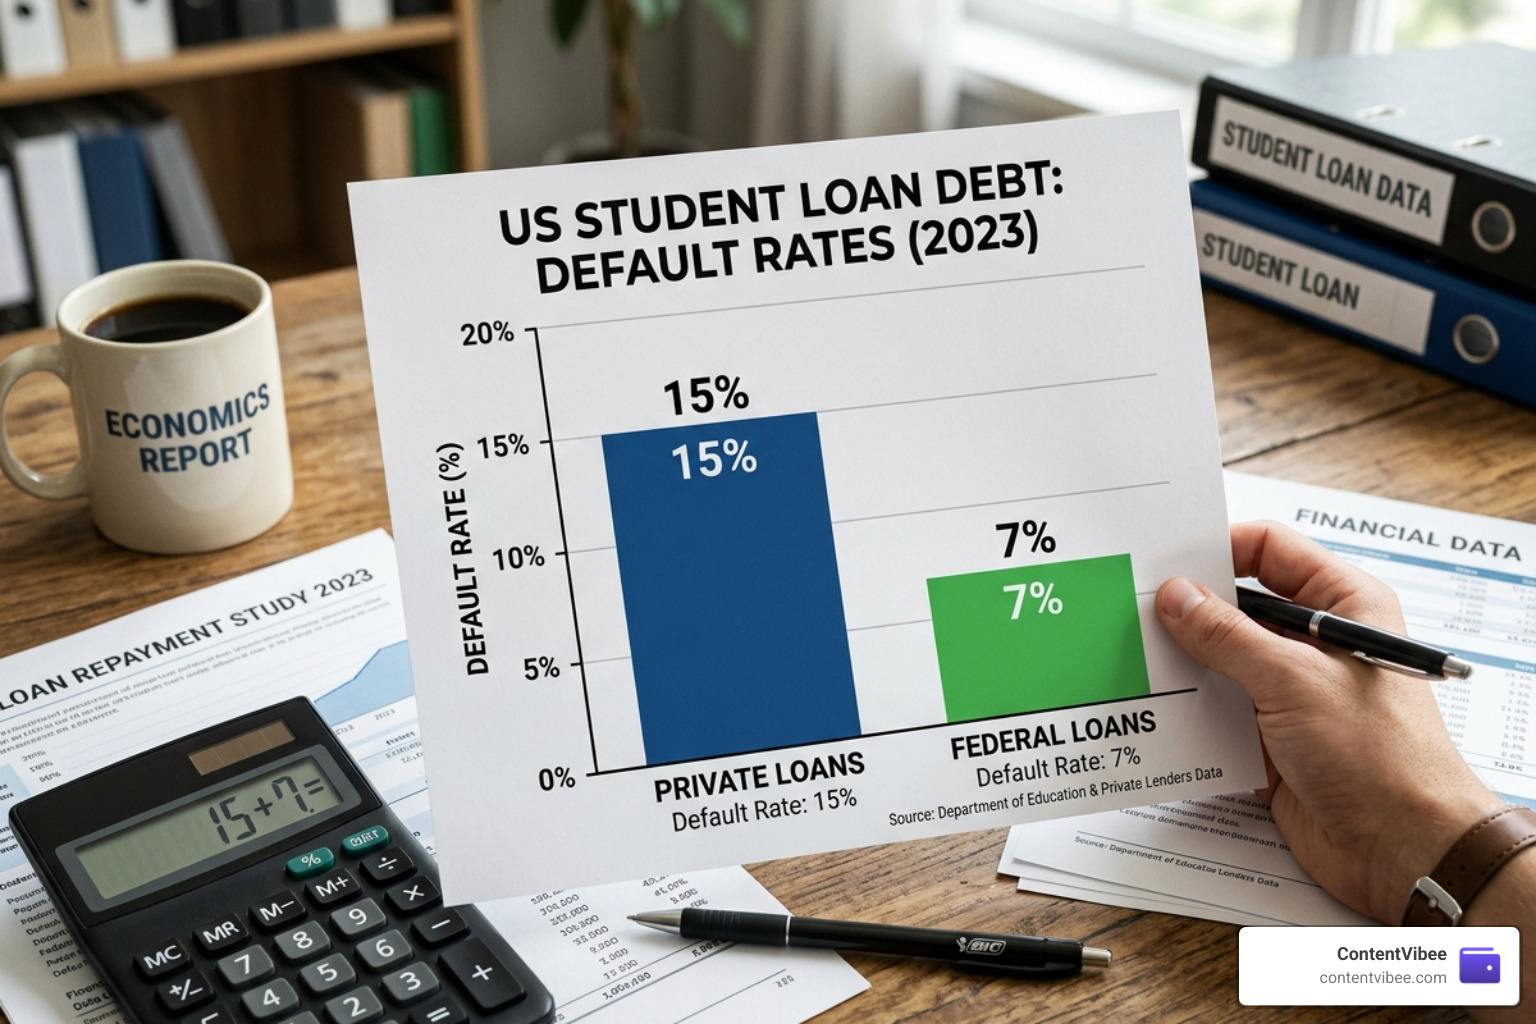
When we look at the landscape of alternative investments in April 2026, Yrefy stands out as a niche player targeting the $200 billion private student loan market. Unlike federal loans, private student loans offer fewer protections for borrowers and cannot be easily discharged in bankruptcy. This creates a unique, albeit high-risk, asset class: distressed private student debt.
To participate in Yrefy, you must be an accredited investor. This means you need a net worth exceeding $1 million (excluding your primary residence) or an individual income of over $200,000 ($300,000 for couples) for the last two years. The entry point is steep, with a $50,000 minimum investment.
Yrefy operates under SEC Regulation D 506(c). This allows them to advertise to the general public, but it also means they are exempt from the rigorous registration and disclosure requirements that apply to public stocks or mutual funds. For many, the central question remains: Is Yrefy A Good Investment? The answer depends entirely on your appetite for illiquidity and your trust in their proprietary "rehabilitation" model.
Analyzing Yrefy Investment Reviews Returns and Borrower Risk Analysis for 2026
When high-yield savings accounts and CDs are normalizing, Yrefy's fixed rates remain eye-catching. As of early 2026, the company offers a tiered return structure based on the length of your commitment:
- 1-Year Term: Approximately 6.25% to 8.0%
- 3-Year Term: Approximately 9.0%
- 5-Year Term: 10.25% fixed annual yield
Data shows that roughly 90% of Yrefy investors opt for the five-year note to capture that 10.25% return. We've found that investors can choose to receive monthly interest payments—providing a steady income stream—or reinvest those earnings to benefit from compounding. While these returns are higher than traditional corporate bonds, they come with the caveat that your principal is tied up in a portfolio of loans held by people who have already defaulted once.
Key Metrics in Yrefy Investment Reviews Returns and Borrower Risk Analysis
One of the most debated statistics in the Yrefy ecosystem is their reported default rate of less than 2%. To put this in perspective, these loans are comprised of borrowers who were previously delinquent or in total default before Yrefy stepped in.
How do they maintain such a low rate? Yrefy claims their "Skip-12" program and hands-on servicing keep borrowers on track. Currently, Yrefy manages a funded portfolio of approximately $100 million, adding $4 million to $6 million in new loan volume each month. The average APR charged to borrowers is just 3.9%, which raises immediate questions about how 10.25% is paid out to investors—a topic we will explore in the business model analysis below.
The Business Model: Profiting from Distressed Private Debt

The engine behind Yrefy is "debt arbitrage." They don't lend new money; they buy old mistakes. Specifically, they network with banks and collection agencies to buy defaulted private student loans at a massive discount—usually 35% to 40% of the original balance.
Once they own the debt, they offer the borrower a lifeline. Instead of the 18% or 22% usury rates the borrower was originally facing, Yrefy refinances the loan at a much lower rate (averaging 3.9%). However, they refinance 105% of the principal and charge a 5% origination fee. This allows the borrower to have a manageable monthly payment while Yrefy attempts to turn a "bad" loan into a performing asset. For a deeper dive into this mechanic, see our guide on Is Yrefy A Smart Investment What You Need To Know/.
Borrower Incentives and Credit Recovery
Why would a borrower choose Yrefy? For many, it is the only way to stop the bleeding of high-interest collections. Yrefy reports that borrowers see an average credit score jump of 125 points within nine months of joining the program, while co-signers (who are involved in 70% of these loans) see an average gain of 140 points.
The Skip-12 program is a major psychological incentive; it allows borrowers to skip one payment every six months (up to 12 times total) during financial hardships without being declared in default. This flexibility is designed to prevent the very defaults that investors fear.
Revenue Spread and Sustainability
This is where the math gets tricky. If Yrefy is charging borrowers an average of 3.9% interest plus a 5% one-time fee, but paying investors 10.25% annually, where does the extra money come from?
The company argues that because they bought the loan at a 60% discount, the "effective yield" on the money they actually spent is much higher. However, critics point to Yrefy's massive marketing spend—over $5.4 million on TV ads and hundreds of thousands to celebrity endorsers—as a red flag. If the interest spread doesn't cover the investor payouts and the heavy overhead, the company must rely on a constant stream of new investor capital to maintain operations.
Critical Risk Assessment: Defaults, Liquidity, and Regulation
Investing in Yrefy is not like buying a Treasury bond. There are three primary pillars of risk: Credit, Liquidity, and Regulatory. Because these are private placements, if the company fails, there is no FDIC insurance to bail you out. According to Yrefy Risks: What You Need to Know - Student Loan Lawyer, the lack of transparency in their audited financials is a significant hurdle for conservative portfolios.
The Reality of Yrefy Investment Reviews Returns and Borrower Risk Analysis in a Volatile Market
In a recession, the first thing people stop paying is unsecured debt like student loans. Yrefy's portfolio is composed entirely of subprime borrowers. While the company claims a <2% default rate, this has largely been during a period of economic stability. A sudden spike in unemployment could devastate the underlying collateral. Furthermore, your investment is illiquid. While there is an early redemption option, it involves a 90-day processing period and potential penalties, making it unsuitable for emergency funds.
Regulatory Red Flags and Legal Challenges
The most significant headwind for Yrefy occurred in February 2025, when the State of Massachusetts fined Yrefy $750,000. The complaint alleged false advertising regarding celebrity endorsers and raised concerns that the "independent collateral agent" touted by the company was actually an interested party. This settlement, reached without an admission of guilt, has led many experts to warn that the marketing may be more polished than the actual financial foundation.
Identity Theft and Credit Fraud Recovery in Distressed Lending
In distressed debt, security is paramount. Borrowers in these portfolios are often targets for further scams. If you are managing your own finances, you should be aware of modern recovery steps:
- unauthorized bank transaction how to dispute and recover money USA 2026: If you notice a withdrawal you didn't authorize, contact your bank within 60 days to trigger Regulation E protections.
- identity theft credit report fraud how to fix and protect your score USA: Use a "security freeze" on all three major credit bureaus to prevent new accounts from being opened in your name.
- wire transfer fraud victim what to do and recovery options USA 2026: Wire transfers are notoriously hard to reverse; immediately contact the FBI's IC3 and the sending bank's fraud department.
Protecting Your Capital: Due Diligence and Financial Security
Before committing $50,000, we recommend a "trust but verify" approach. Yrefy provides a Private Placement Memorandum (PPM), but it is a dense legal document. You should specifically look for their debt-to-equity ratio and how they handle "capital calls" if defaults rise.
| Risk Tier | Potential Impact | Mitigation Strategy |
|---|---|---|
| Borrower Default | Loss of interest income | Diversification across thousands of loans |
| Company Insolvency | Potential loss of principal | Asset-backed security (collateralized notes) |
| Regulatory Action | Halted operations/fines | Monitoring SEC and State filings |
Liquidity and Asset Protection
Because there is no secondary market for Yrefy notes, you are effectively "married" to the investment for the duration of the term (1-5 years). If you need your money back because of a zelle fraud transaction recovery steps and bank protection options USA situation or a personal emergency, you may find your capital locked away. Always ensure that Yrefy represents no more than 5-10% of your total fixed-income allocation.
Enhancing Portfolio Security Against Financial Scams
As an accredited investor, you are a "high-value target" for fraudsters. Be wary of any investment that uses heavy celebrity endorsements without providing audited financial statements. To protect yourself from an irs tax refund scam how to claim loss and prevent identity theft USA, always file your taxes early and use an IP PIN (Identity Protection PIN) provided by the IRS.
Frequently Asked Questions about Yrefy
Is Yrefy a legitimate investment or are there red flags?
Yrefy is a legitimate company in the sense that it is a registered business that has been paying investors since 2017. However, the $750,000 Massachusetts fine and the high marketing costs compared to borrower interest rates are considered significant "red flags" by many financial analysts.
How does Yrefy pay 10.25% if borrowers only pay 3.9%?
Yrefy's model relies on the fact that they buy the debt at a 60% discount. If they buy a $10,000 loan for $4,000, and the borrower pays 3.9% on the original $10,000, the "yield on cost" for Yrefy is much higher than 3.9%. However, this math must also cover their 5% marketing/operating costs and investor payouts, which leaves a very thin margin for error.
Can I lose my principal investment with Yrefy?
Yes. Unlike a bank account, Yrefy is not FDIC-insured. If the underlying borrowers stop paying en masse, or if the company faces a liquidity crisis, investors could face a partial or total loss of their principal.
Conclusion
At ContentVibee, our goal is to help you navigate the complex world of alternative finance with clarity. Yrefy Investment Reviews Returns and Borrower Risk Analysis reveals a product that offers high rewards but carries "tail risks" that traditional investments do not. If you are an accredited investor with a high risk tolerance and a desire for social impact (helping students escape debt), Yrefy might have a place in your portfolio. However, for those seeking guaranteed safety, the regulatory history and illiquidity suggest caution. Always perform your own due diligence and consult with a fiduciary advisor before moving capital into private placements.
For More info about investment reviews, stay tuned to our latest deep dives into the fintech and alternative lending space.