


Why Millions of Americans Choose the Same P2P Payment App as Their Friends
Why choose a p2p payment service your friends use comes down to one simple idea: money moves fastest when everyone is on the same platform.
Here are the top reasons to match your friends' P2P app choice:
- Instant transfers - No delays waiting for a recipient to create an account
- Zero friction - No failed payments or "payment purgatory" from cross-platform incompatibility
- Easier bill splitting - Group expenses like dinner or rent resolve in seconds
- Faster setup - Skip extra verification steps when your contacts already use the app
- Social trust - Widely adopted apps like Venmo, Zelle, and Cash App have proven security track records
Think about the last time you split a dinner bill. One person pays the full tab on their card, and everyone else needs to pay them back right now. If your friend uses Venmo and you use a different app, that simple $15 reimbursement suddenly becomes an awkward IOU.
That friction is exactly why 64% of all Americans now use at least one P2P payment app — and why 79% use one of the major platforms. The app your social circle already uses isn't just convenient. It's the only one that actually works seamlessly for your real-life transactions.
The network effect is real: an app is only as useful as the number of people you know who also have it.
Why Choose a P2P Payment Service Your Friends Use for Maximum Convenience
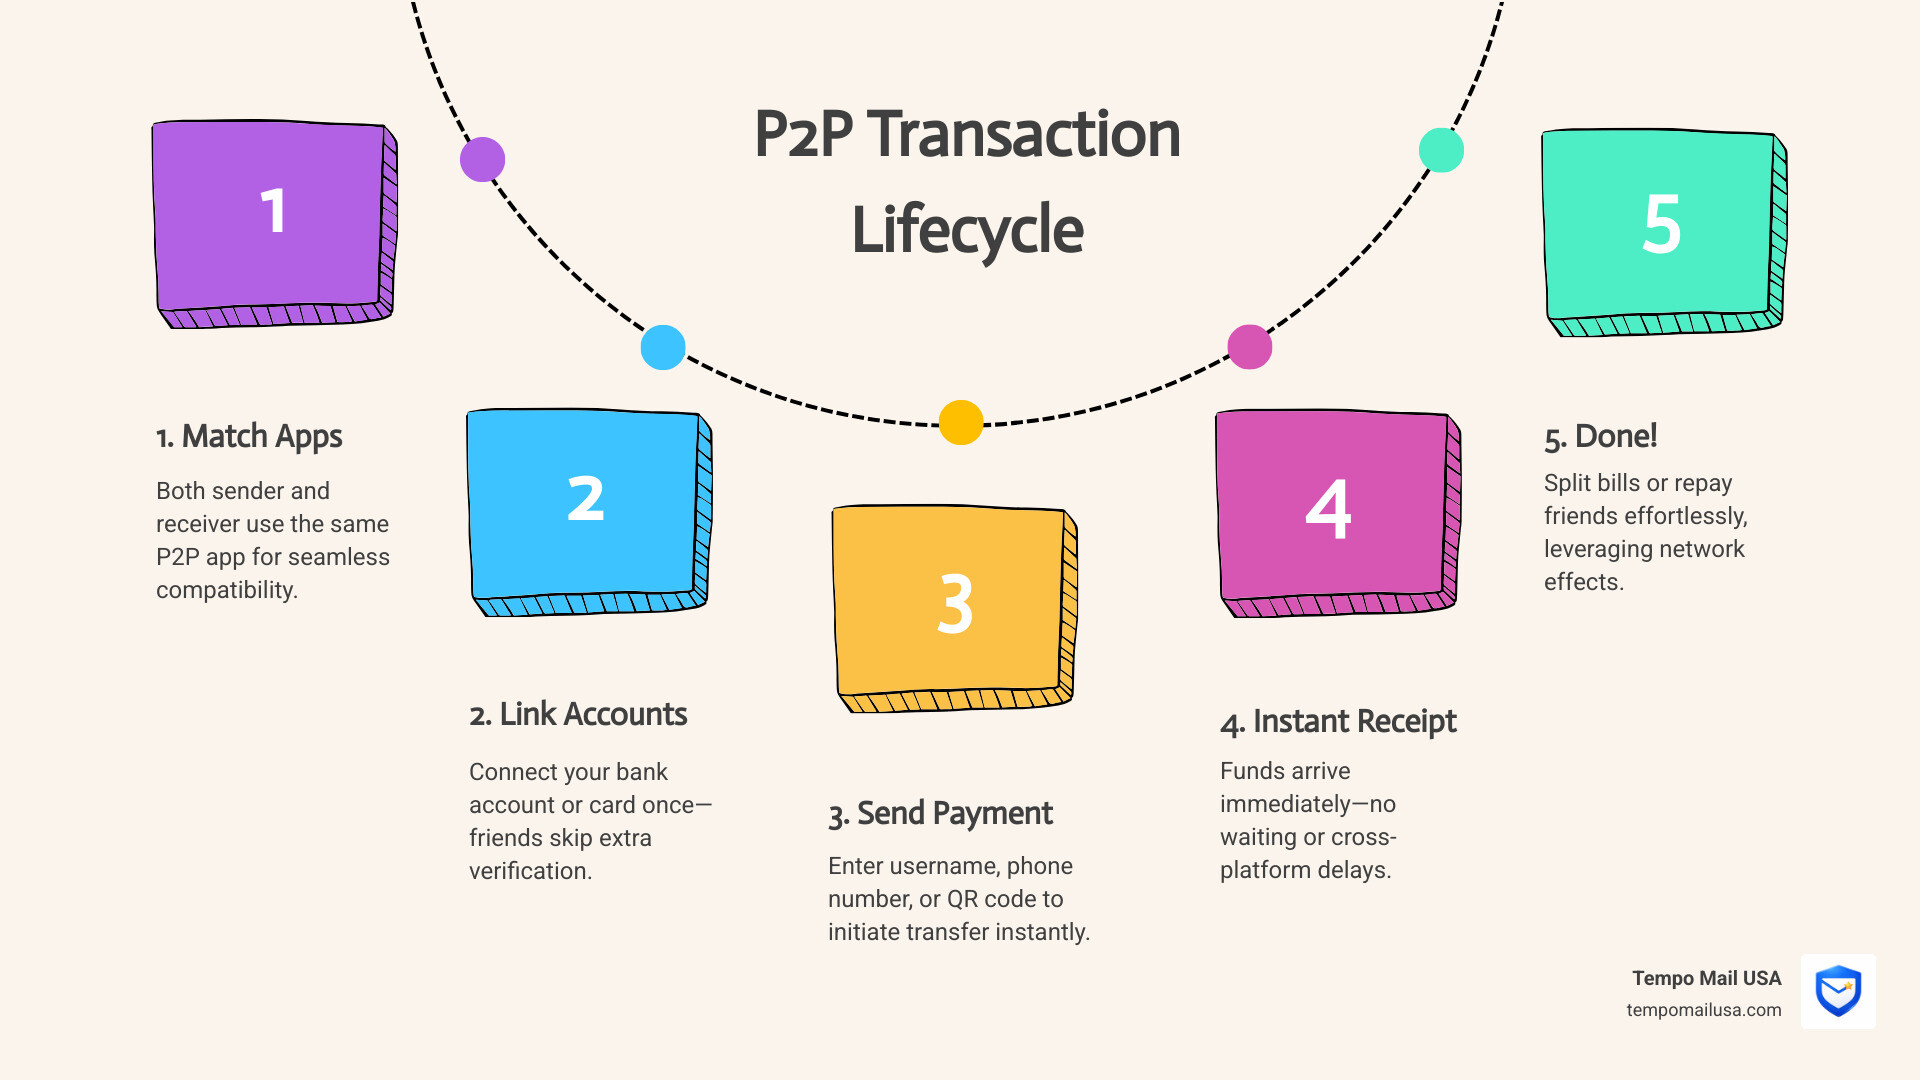
When we talk about "network effects," we are describing a service that becomes more valuable as more people join it. In finance, this is exactly why choose a p2p payment service your friends use. If everyone in your group chat is on Venmo, downloading a different app makes you the "outlier" who complicates every group dinner.
Statistics show that P2P adoption is skyrocketing. Roughly 79% of Americans use a major service like Venmo, PayPal, or Cash App. Among those aged 18 to 29, that number jumps to a staggering 81%. When you align with the majority, you tap into a pre-built ecosystem of financial convenience.
According to What Are Peer-to-Peer Payments?, these platforms allow for direct digital transfers without the need for traditional checks or cash. By choosing the same app as your peers, you drastically reduce setup time and verification hassles. Many apps allow you to find contacts instantly via your phone’s address book. If they are already verified, the "trust factor" is established by the platform, making your first transaction as smooth as a handshake.
| Feature | High-Adoption App (e.g., Venmo/Zelle) | Low-Adoption/Niche App |
|---|---|---|
| Transaction Speed | Instant to Minutes | 1-3 Business Days (Inter-bank) |
| User Adoption | 64% - 79% of U.S. Adults | < 5% of U.S. Adults |
| Setup Friction | Low (Syncs with Contacts) | High (Manual Invites Needed) |
| Verification | Rapid via existing network | Lengthy Document Uploads |
Seamless Compatibility: Why Choose a P2P Payment Service Your Friends Use to Avoid Delays
We have all been there: you send money to a friend via an app they don't have. Instead of receiving the cash, they get a cryptic text message asking them to "claim" their funds by creating a new account and linking a bank. This is what experts call "payment purgatory."
When you use a different service than your contacts, you risk failed transfers or significant delays. For example, while Zelle moves money directly between bank accounts for over 1,700 financial institutions, trying to send money from a non-partner bank to a partner bank can result in multi-day holds.
To avoid this, we recommend choosing the platform your social circle prefers. However, joining these platforms often requires sharing your primary email address—a piece of personally identifiable information (PII) that can be sold to advertisers or leaked in a breach. Using secure payment aliases from Tempo Mail USA allows you to sign up for these high-convenience apps without exposing your permanent digital identity to potential tracking.
Social Financial Integration: Why Choose a P2P Payment Service Your Friends Use for Group Expenses
The true power of P2P is felt during group activities. Whether it’s splitting a $60 pizza bill among six friends or pooling money for a baby shower gift, having everyone on one platform turns a logistical nightmare into a three-tap process.
As noted in 11 Advantages & Disadvantages of Peer-to-Peer (P2P) Payment Apps, these apps offer features like built-in bill splitting and payment requests. If you are the roommate responsible for the $2,000 rent, you can send out "requests" to your housemates. They simply tap "pay," and the money is in your digital wallet instantly. This eliminates the need for awkward conversations about informal loans or digital IOUs.
Protecting Your Financial Data with Identity Theft Protection Services
While convenience is king, we must address the "elephant in the room": security. Because P2P payments are often irreversible—functioning much like digital cash—they are prime targets for fraudsters. This is where identity theft protection services become non-negotiable.
When you link your bank account to a P2P app, you are creating a digital bridge to your life savings. We highly suggest utilizing credit monitoring software to keep an eye on any unauthorized attempts to open accounts in your name. Furthermore, businesses using P2P for disbursements must ensure data privacy compliance to protect their customers' sensitive information.
For individuals, cybersecurity insurance is an emerging strategy to mitigate the risk of financial loss from sophisticated social engineering scams. Most P2P platforms use encryption and biometric authentication (like FaceID), but these don't protect you if you are tricked into sending money to a scammer.
Security Checklist for Linking Bank Accounts:
- Enable Two-Factor Authentication (2FA): Never rely on just a password.
- Use Biometrics: Require a fingerprint or facial scan for every transaction.
- Set Transaction Limits: Cap the amount that can be sent in a single day.
- Verify the Handle: Always double-check the recipient's @username or QR code.
- Monitor Notifications: Turn on "push" alerts for all incoming and outgoing transfers.
Preventing Phishing with Disposable Email Infrastructure
One of the greatest risks to your financial security isn't the payment app itself, but the email address you use to sign up. Your primary email is the "master key" to your digital life. If a P2P service suffers a data breach, your email is the first thing hackers will use to launch phishing attacks.
This is why we at Tempo Mail USA advocate for disposable email infrastructure. Our service provides a "PII firewall" by offering temporary email aliases that proxy your real identity. When you protect your primary inbox today, you ensure that if a payment service's database is compromised, the hackers only get a proxy address that you can delete at any time.
Using temporary emails for P2P sign-ups offers several "Enterprise-grade" benefits for the everyday user:
- Anonymous Sign-ups: Keep your real name and primary email off of marketing lists.
- Tracking Pixel Blocking: Prevent companies from knowing when and where you open their transaction receipts.
- Malicious Payload Defense: If a "fake" payment notification is sent to your proxy email, it is isolated from your main communication hub.
- Phishing Mitigation: Since your real email isn't on the app, any "Urgent Account Update" sent to your main inbox is an obvious fraud.
Advanced Malware Protection and Enterprise VPN Solutions for Mobile Payments
Sending money while sitting at a coffee shop? You might be walking into a trap. Public Wi-Fi is notorious for "man-in-the-middle" attacks, where hackers intercept data packets as they travel from your phone to the payment server. To combat this, enterprise VPN solutions are essential for anyone handling financial transactions on the go.
A VPN creates an encrypted tunnel for your data, ensuring that even if the Wi-Fi is compromised, your bank details remain unreadable. Combined with advanced malware protection on your mobile device, you create a formidable defense against "overlay" attacks—where malicious software draws a fake login screen over your real payment app to steal your credentials.
Furthermore, for those running a side hustle, secure cloud storage for business is vital for keeping records of P2P transactions without exposing them to local device theft.
Frequently Asked Questions about P2P Security and Privacy
Are P2P payments safe for large transactions?
Generally, P2P payments are designed for small, informal transfers between trusted individuals. For large transactions (like a car down payment), traditional wire transfers or cashier's checks are safer because they offer better fraud recourse and cybersecurity insurance protections. Most P2P apps have strict daily limits to prevent massive losses.
How do identity theft protection services interact with payment apps?
Identity theft protection services monitor the dark web for your linked credentials. If your P2P login info is leaked, these services alert you immediately so you can change your password and unbind your bank account before a thief can drain your funds. They act as an early warning system for your mobile wallet.
Why is data privacy compliance critical for P2P providers?
Data privacy compliance (like GDPR or CCPA) forces P2P providers to be transparent about how they use your data. It ensures they use high-level encryption and gives you the right to request that your data be deleted. Without these regulations, your financial habits could be sold to the highest bidder without your consent.
Can enterprise VPN solutions prevent P2P payment fraud?
While an enterprise VPN solution prevents data interception on public networks, it cannot stop "authorized" fraud—where you are tricked into sending money to a scammer. VPNs protect the connection, but you must still use advanced malware protection and common sense to protect the transaction.
Conclusion
Choosing a P2P payment service that your friends use is the smartest way to navigate the modern financial landscape. It maximizes convenience, eliminates the "purgatory" of failed transfers, and turns group expenses into a breeze. However, as we move toward a cashless society, the need for advanced malware protection and financial privacy has never been higher.
By combining the social benefits of popular P2P apps with the security of identity theft protection services and enterprise VPN solutions, you can enjoy the speed of digital payments without the stress of data exposure. Don't let your primary email become a liability. Secure your digital footprint at TempoMailUSA.com and use our secure identity proxying to keep your PII behind a permanent firewall. Stay connected, stay paid, and most importantly, stay private.