


Why Retirement Calculator Accuracy and Long Term Investment Growth Strategy Diverge
When we sit down to plan our future, we often treat retirement calculators like crystal balls. We plug in a few numbers and expect a definitive date for our "freedom day." However, there is a massive gap between a simple math equation and the messy reality of the stock market. The reason Why Every Retirement Calculator Gives You Different Numbers usually comes down to hidden assumptions.
One tool might assume a steady 7% return every single year, while another factors in the "sequence of returns risk"—the danger of a market crash happening right when you stop working. Furthermore, the Retirement Calculator Accuracy and Long Term Investment Growth Strategy you choose is heavily influenced by inflation variance. If one calculator assumes 2% inflation and another assumes 3%, the projected cost of your lifestyle thirty years from now could differ by $400,000 or more.
To get a clearer picture, we recommend using a robust Financial Retirement Planner that allows you to toggle these variables. Understanding that these tools are "maps, not timetables" is the first step toward a more reliable plan.
Optimizing Your Retirement Calculator Accuracy and Long Term Investment Growth Strategy
Accuracy starts with the quality of your inputs. Most people suffer from "optimism bias," underestimating their future expenses by 15-25%. When using a Retirement Calculator, we need to be brutally honest about our spending.
Don't just look at your current bills. Think about "one-time" expenses that happen every few years: roof repairs, new cars, or family weddings. Additionally, consider your salary increases. Many tools, like the NerdWallet calculator, default to a 2% annual pay raise. If you’re in a high-growth career, this might be too low; if you’re near your earning ceiling, it might be too high. Precision here prevents you from reaching age 65 only to realize your "nest egg" is actually a "birdseed budget."
The Impact of Fees on Retirement Calculator Accuracy and Long Term Investment Growth Strategy
Fees are the silent killers of retirement dreams. A 1% annual fee sounds small, but it can reduce a $500,000 portfolio by approximately $150,000 over 20 years. Many calculators ignore investment fees entirely, showing you a "gross" return rather than what you actually get to keep.
When we use tools like the Ramsey Investment Calculator, it’s vital to subtract your fund's expense ratios from your expected return. If you expect the market to return 8% but you're paying 1% in management fees and 0.5% in fund expenses, your real growth is only 6.5%. Over a 30-year career, that 1.5% gap can mean the difference between retiring in comfort or looking for part-time work in your 70s.
Critical Assumptions: Inflation, Taxes, and Real Returns

To master your Retirement Calculator Accuracy and Long Term Investment Growth Strategy, you must distinguish between "nominal" and "real" returns. Nominal is the number you see on your statement; real is what you can actually buy with it.
Historically, the S&P 500 has returned about 10-12% annually. However, after accounting for the historical inflation average of 3.1%, the "real" return is closer to 7-8%. In the last decade, the S&P 500 real return was roughly 10.75% (13.78% nominal minus 3.03% inflation), but we shouldn't assume the next decade will be as generous.
Taxes are the other major "hidden" factor. If you have $1 million in a Traditional 401(k), the IRS owns a significant chunk of that. Using an AI Income Tax Calculator can help you estimate your future tax bracket so you don't overestimate your spendable income.
Table: Tax-Deferred vs. Tax-Free Growth (Hypothetical $100k Investment over 20 Years at 7%)
| Feature | Traditional IRA (Tax-Deferred) | Roth IRA (Tax-Free) |
|---|---|---|
| Starting Balance | $100,000 | $100,000 |
| Ending Balance (Pre-Tax) | $386,968 | $386,968 |
| Estimated Tax (22%) | ($85,133) | $0 |
| Spendable Total | $301,835 | $386,968 |
Choosing Realistic Investment Return Rates
One of the biggest mistakes we see is using "aggressive" return rates for the entire duration of a plan. Is Your Retirement Calculator Designed for Accuracy? Most high-fidelity tools suggest a tiered approach:
- Pre-retirement (Accumulation Phase): 6-7% is a conservative, realistic target for a diversified portfolio.
- Post-retirement (Distribution Phase): 4-5% is safer as you shift toward bonds and cash to protect your principal.
Relying on a 10% return in retirement is a recipe for disaster. If the market dips by 20% in your first year of retirement while you are also withdrawing 4%, your portfolio may never recover.
Why Account Types Matter for Accurate Projections
We cannot stress this enough: account types change everything in Finance. A calculator that treats all "savings" the same is fundamentally flawed.
- Brokerage Accounts: Subject to capital gains taxes and annual tax drag on dividends.
- Traditional IRA/401(k): Taxed as ordinary income upon withdrawal.
- Roth IRA/401(k): Completely tax-free.
Accurate modeling requires "withdrawal sequencing"—deciding which account to tap first to minimize the IRS's share. Generally, we want to let tax-free Roth accounts grow the longest.
Stress-Testing Your Plan Against Market Volatility and Longevity Risk
A "successful" retirement plan isn't one that works when the sun is shining; it’s one that survives a storm. This is where Monte Carlo simulations come in. Instead of a straight line, these simulations run your plan through 1,000+ market scenarios, including "Great Depression" style crashes.
We also have to face "longevity risk"—the "risk" of living too long. If you plan for your money to last until age 85 but live to 95, those last ten years will be incredibly difficult. Will Your Retirement Savings Last? A Practical Calculator Guide suggests planning to at least age 95, especially for couples, as there is a 25% chance one spouse will reach that milestone.
Modeling Social Security and RMDs
Social Security is a major lever in your Retirement Calculator Accuracy and Long Term Investment Growth Strategy. Delaying your claim from age 62 to 70 increases your monthly benefit by approximately 76%. For many, this is the best "guaranteed return" available.
You also need to plan for Required Minimum Distributions (RMDs). Currently starting at age 73, these mandatory withdrawals can push you into a higher tax bracket and even increase your Medicare premiums. If you have a large balance in a traditional 401(k), you might want to use a Mortgage Calculator to see if paying off your home early with that taxable income makes sense before RMDs kick in.
Accounting for Healthcare and Long-Term Care Costs
Healthcare is the "wild card" of retirement. The average 65-year-old couple retiring today needs approximately $315,000 just for medical expenses. This does not include long-term care, which can cost $50,000 to $100,000+ per year.
Because healthcare inflation (5-6%) typically outpaces general inflation, your calculator needs to account for these rising costs separately. If you find yourself facing a medical debt crisis, tools like a Loan Calculator can help you model repayment, but proactive saving in an HSA (Health Savings Account) is a much better strategy.
Catch-Up Strategies and Financial Recovery for Late Starters
If you’re starting late, don't panic—but do get aggressive. The "catch-up" provision allows those 50 and older to contribute extra to their 401(k) and IRA. In 2026, the 401(k) limit for those 50+ is $31,000.
Another powerful lever is delaying retirement by just two or three years. This provides a "triple benefit": more years of contributions, more years of compound growth, and fewer years of withdrawals. If debt is holding you back, use a Debt Payoff Calculator to create a "snowball" or "avalanche" plan to clear your balance before you stop working.
Closing the Savings Gap with Aggressive Growth
To Earn Money and close the gap, many late starters look toward side hustles or downsizing their primary residence. Selling a large family home and moving to a lower-cost area (geographic arbitrage) can instantly add six figures to your retirement nest egg.
If you have multiple high-interest debts, a Debt Consolidation Calculator can show you how much you could save by rolling those balances into a lower-interest loan, freeing up more cash to dump into your 401(k).
Protecting Your Financial Identity During Retirement Planning
As you move large sums of money between accounts or search for financial advice online, you become a high-value target for identity thieves. Sophisticated "unauthorized bank transaction" scams often target retirees because their accounts are well-funded.
Protecting your Social Security number and financial identity is just as important as your asset allocation. One way we help users is through TempoMailUSA, which provides temporary email aliases. By using an alias when signing up for financial newsletters, retirement tools, or investment forums, you create a firewall between your real identity and potential hackers. This prevents your primary email—often linked to your bank accounts—from ending up on "sucker lists" used for phishing and wire transfer fraud. While you use a Student Loan Repayment Calculator to help a child or grandchild, ensure your own digital footprint is secure.
Frequently Asked Questions about Retirement Calculator Accuracy
Why do different calculators give me different results for the same data?
The primary reason is "hidden assumptions." Calculators differ in how they handle inflation, whether they include investment fees, their default life expectancy, and how they model taxes. A "low-fidelity" calculator might assume a flat 3% inflation and 7% return, while a "high-fidelity" tool uses Monte Carlo simulations to show a range of probable outcomes.
What is the most common error people make when using a retirement tool?
Underestimating expenses is the #1 error. Most people assume they will spend less in retirement, but "active" early retirement years (travel, hobbies) can be more expensive than working years. Additionally, people often forget to account for the "tax bite" on Traditional 401(k) and IRA withdrawals.
How often should I update my retirement projections?
We recommend an annual "check-up." You should also immediately reassess your plan after major life events, such as a career change, a significant inheritance, a health diagnosis, or a major market downturn.
Conclusion
Building a secure future requires more than just a lucky guess. By focusing on Retirement Calculator Accuracy and Long Term Investment Growth Strategy, you move from "hoping" to "knowing." Remember to use conservative return rates, account for the eroding power of inflation, and never ignore the impact of taxes and fees.
Financial security also requires digital security. In an era where "identity theft credit report fraud" is rampant, protecting your personal information is vital. TempoMailUSA offers a secure way to interact with the financial world without exposing your permanent identity to every service you try.
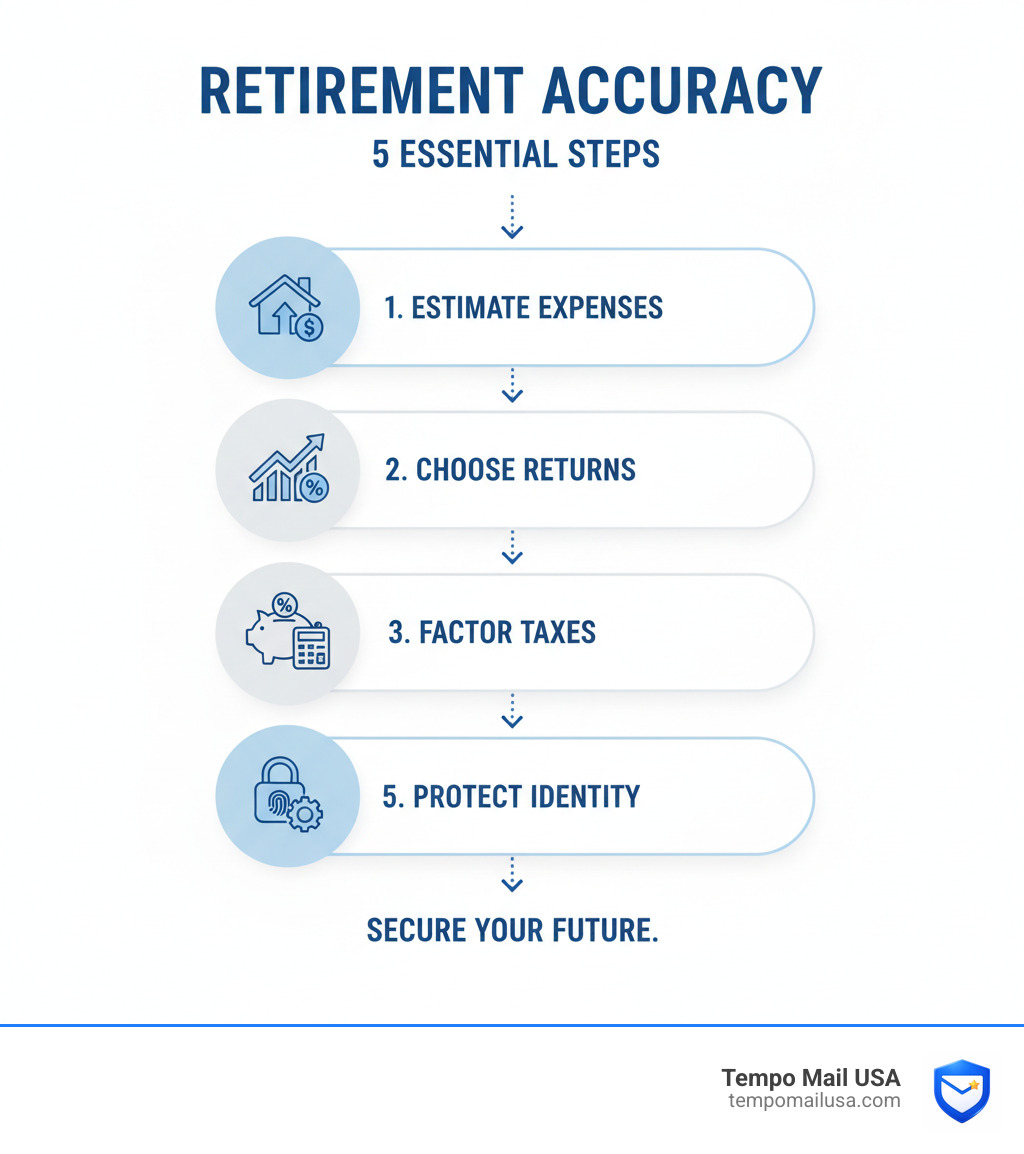
Secure your financial future and protect your data at TempoMailUSA today to ensure your path to retirement is both prosperous and private.