


Best High Yield Savings Account Rates: Quick Answer
High yield savings account rates are currently as high as 4.21% APY — roughly 7 times the national average of 0.59% — making them one of the most accessible ways to grow your cash safely right now. To explore these options without compromising your privacy, using a tool like Tempo Mail USA can shield your personal information from unwanted marketing during your search.
Top High Yield Savings Account Rates (April 2026)
| Bank | APY | Minimum Deposit |
|---|---|---|
| Axos Bank | 4.21% | None |
| Vio Bank | 4.03% | $100 |
| LendingClub | 4.00% | None |
| Bread Savings | 4.00% | $100 |
| Openbank | 4.00% | $500 |
All of the accounts above are FDIC-insured up to $250,000 per depositor. None charge monthly fees.
Here's the situation in plain terms: the Federal Reserve cut rates three times at the end of 2025, bringing the federal funds rate to 3.50–3.75%. That's put some downward pressure on savings rates — but the best online banks are still offering yields that comfortably outpace the current 3.0% inflation rate.
That's a genuinely rare window. Your emergency fund can actually grow in real terms, not just tread water.
The catch most people don't think about? Every time you open a new online bank account, you're handing over your Social Security number and personal email address. Using a privacy tool like Tempo Mail USA allows you to research the best high yield savings account rates without leaving your primary inbox vulnerable to data breaches or spam.
We'll cover both sides: how to find the best rate and how to use a "PII firewall" to keep your identity safe.
Understanding High Yield Savings Account Rates in 2026
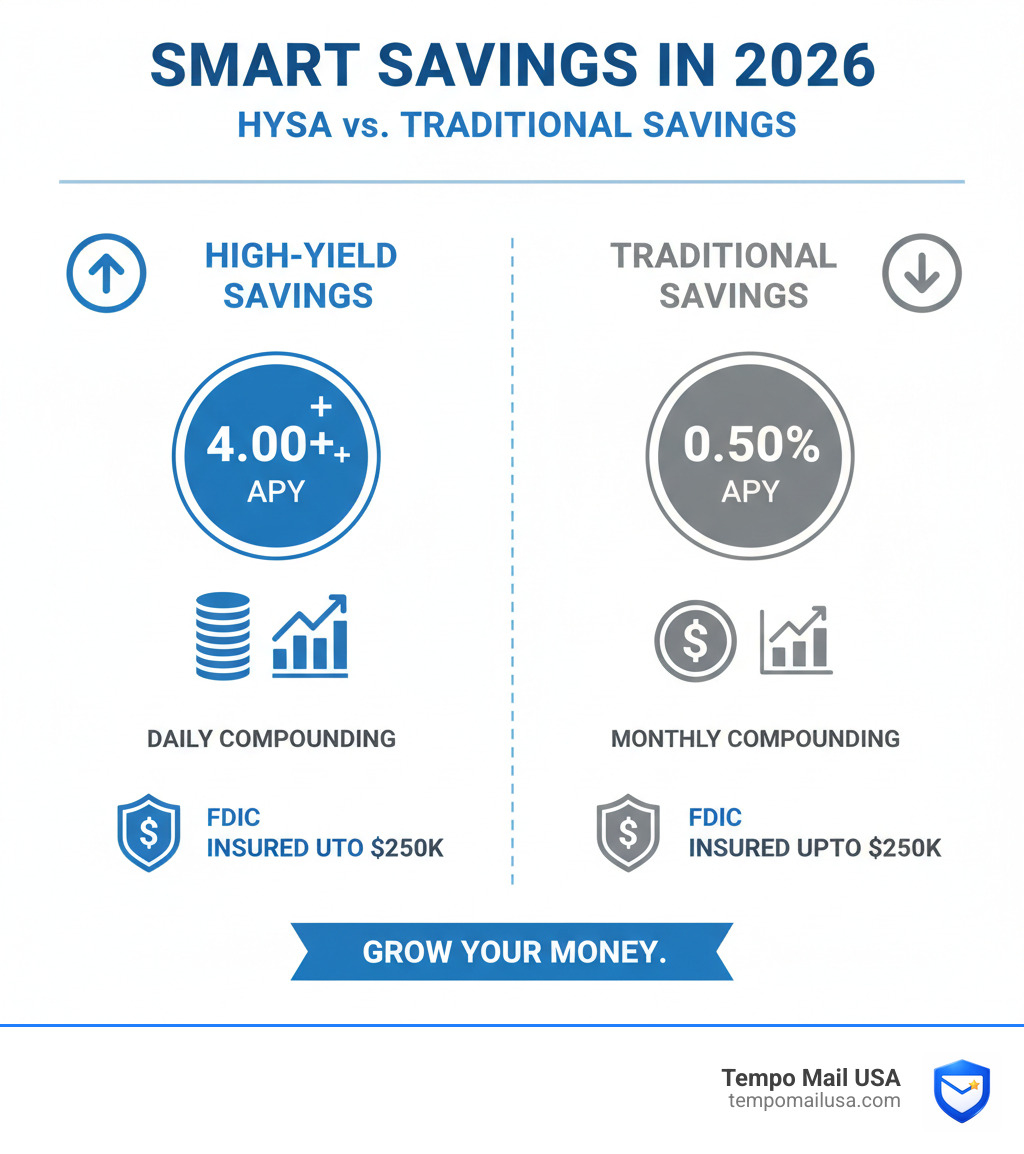
To understand high yield savings account rates, we first have to look at the mechanics of the Annual Percentage Yield (APY). Unlike a simple interest rate, APY accounts for the effect of compounding. In HYSAs, interest typically compounds daily and is credited to your account monthly. This means you earn interest on your interest every single day.
As of April 2026, the financial landscape is shaped by a Federal funds rate sitting between 3.50% and 3.75%. While this is lower than the peaks of previous years due to three rate cuts at the end of 2025, the "spread"—the difference between what banks pay you and what inflation takes away—is still in your favor. With inflation currently at 3.0% (based on September 2025 data), any account yielding over 4% is providing a "real" return.
The High Yield Savings Accounts - April 2026 Rates currently available show that online-only institutions remain the most competitive. Because these banks don't have the overhead of physical branches, they can pass those savings on to us in the form of higher yields.
Why Axos Bank Leads High Yield Savings Account Rates
Currently, Axos Bank holds the top spot with a 4.21% APY. To put that into perspective, the national average for a standard savings account is a meager 0.59%. By choosing a leader like Axos, you are earning roughly 7 times more interest than the person leaving their money in a "big name" traditional brick-and-mortar bank.
What makes this particular rate impressive isn't just the number; it's the lack of friction. Many high-interest accounts come with "hoops" to jump through—monthly direct deposits, a minimum number of debit card swipes, or massive opening balances. Axos manages to lead the pack while maintaining a digital-first approach that prioritizes ease of use and zero monthly maintenance fees.
Protecting Your Data While Chasing High Yield Savings Account Rates
We often talk about "rate chasing"—the act of moving money from one bank to another to capture an extra 0.10% or 0.20% APY. While this is great for your wallet, it can be a nightmare for your digital privacy. Every time you "shop" for the Best High-Yield Savings Accounts Of March 2026 - Up to 4.21% | Bankrate, you are likely entering your email address into lead-generation forms or bank applications.
This is where the "PII Firewall" concept becomes vital. At Tempo Mail USA, we see how financial institutions and the marketing firms they hire use your primary email address to track your behavior across the web. By using a secure email alias from TempoMailUSA, you can shield your real identity during the research phase.
Furthermore, once you choose a bank, ensure you enable Two-Factor Authentication (2FA) and use a dedicated, secure connection. If you are managing your high-yield accounts on public Wi-Fi—perhaps at a café while checking your balances—you are at risk. We highly recommend using NordVPN to encrypt your traffic and keep your financial data away from prying eyes.
Top 5 High Yield Savings Account Rates Analyzed
When comparing high yield savings account rates, it is important to look at the fine print. A high rate is only "high" if it isn't eaten away by hidden fees or if you can actually meet the requirements to open the account.
| Institution | APY | Min. to Earn APY | Key Feature |
|---|---|---|---|
| Axos Bank | 4.21% | $0 | No monthly fees; 24/7 digital access |
| Vio Bank | 4.03% | $100 | No minimum balance required after opening |
| LendingClub | 4.00% | $0 | Smooth external account linking |
| Bread Savings | 4.00% | $100 | Simple, no-frills interface |
| Openbank | 4.00% | $500 | Backed by Santander; high reliability |
While Axos takes the gold, Vio Bank is a very strong runner-up at 4.03% APY. LendingClub and Bread Savings both offer a solid 4.00%, which is still significantly higher than the 0.6% national average seen in late March. Openbank, the digital arm of Santander, also offers 4.00% but requires a slightly higher initial deposit of $500.
The Hidden Risks: Security and Data Privacy in Online Banking
The move toward online-only banking has been a boon for our savings goals, but it has expanded the "attack surface" for cybercriminals. When you open an HYSA, you provide the "Holy Trinity" of identity theft: your Social Security Number, your full legal name, and your physical address.
If a bank suffers a data breach, this Personally Identifiable Information (PII) ends up on the dark web. Phishing scams are also becoming more sophisticated; you might receive a perfectly formatted email from "your bank" asking you to "verify your account" because of a suspicious login.
To mitigate these risks:
- Use an Alias: Use Tempo Mail USA for your initial inquiries and newsletters to keep your primary inbox clean and your identity masked.
- Verify Insurance: Always ensure the bank is Member FDIC (Federal Deposit Insurance Corporation). This protects your money up to $250,000 if the bank goes bust.
- Secure Your Connection: Never log into your high-yield account without a VPN. A tool like NordVPN ensures that even if the Wi-Fi network is compromised, your login credentials remain encrypted.
How to Choose and Open the Best HYSA
Choosing the right account is about more than just the highest number. You need to consider your own liquidity needs. Most HYSAs allow for easy transfers to and from your external checking account, but keep in mind that these transfers can take 1 to 3 business days.
Here is our checklist for choosing the best account:
- APY Consistency: Does the bank have a history of staying competitive, or do they offer a "teaser rate" that drops after three months?
- Fee Structure: Avoid any account with a "monthly maintenance fee." In 2026, there is no reason to pay a bank to hold your money.
- Minimums: Some banks require a $5,000 balance to earn the top rate. If you only have $1,000, you might earn a much lower rate.
- User Experience: Is the mobile app highly rated? Can you deposit checks via your phone?
Before you commit, it helps to see the math in action. You can Calculate your interest growth to see exactly how much a 4.21% APY will earn you over 12 months compared to a standard account. For example, on a $10,000 deposit, a 4.21% rate earns you roughly $421 a year, while a 0.59% account earns you only $59. That’s $362 for doing absolutely nothing other than choosing a better bank.
Alternatives to High-Yield Savings Accounts
While high yield savings account rates are excellent for liquidity, they aren't the only game in town. Depending on your goals, you might want to "ladder" your savings across different products.
- Certificates of Deposit (CDs): If you don't need your money for 12 to 14 months, you can often lock in a rate slightly higher than an HYSA. However, you'll face a penalty if you withdraw early.
- Money Market Accounts (MMAs): These are hybrid accounts that offer high interest like a savings account but often come with a debit card or check-writing abilities.
- Treasury Bills: These are backed by the U.S. government and are currently very competitive.
- SGOV ETF: For those with brokerage accounts, the iShares 0-3 Month Treasury Bond ETF (SGOV) provides a way to earn yield on cash with high liquidity, often tracking very closely with the top HYSA rates.
Frequently Asked Questions about High Yield Savings
What is the difference between a HYSA and a traditional savings account?
The primary difference is the interest rate; HYSAs offer yields significantly higher than the 0.59% national average by operating online with lower overhead costs. While traditional accounts offer physical branches, HYSAs prioritize wealth accumulation through superior APYs.
Are high-yield savings accounts safe?
Yes, HYSAs are safe as long as they are FDIC or NCUA insured, which protects your deposits up to $250,000 per depositor. This federal backing ensures your money is recovered even if the bank fails.
Do I have to pay taxes on HYSA interest earnings?
Yes, interest earned in a HYSA is considered taxable income by the IRS and must be reported on your annual tax return. You will receive a Form 1099-INT if you earn more than $10 in interest during the year.
Conclusion
Maximizing your high yield savings account rates is one of the simplest "wins" in personal finance. Whether you are building an emergency fund or saving for a house down payment, the difference between a standard account and a top-tier HYSA like Axos or Vio Bank can mean hundreds of dollars in extra interest over time.
However, as you navigate the digital banking world of 2026, don't let your quest for yield compromise your personal security. To protect your financial journey, we recommend using Tempo Mail USA to mask your identity during the application process and NordVPN to secure your online banking sessions. By combining smart financial choices with robust privacy practices, you can grow your wealth while keeping your digital footprint secure.