

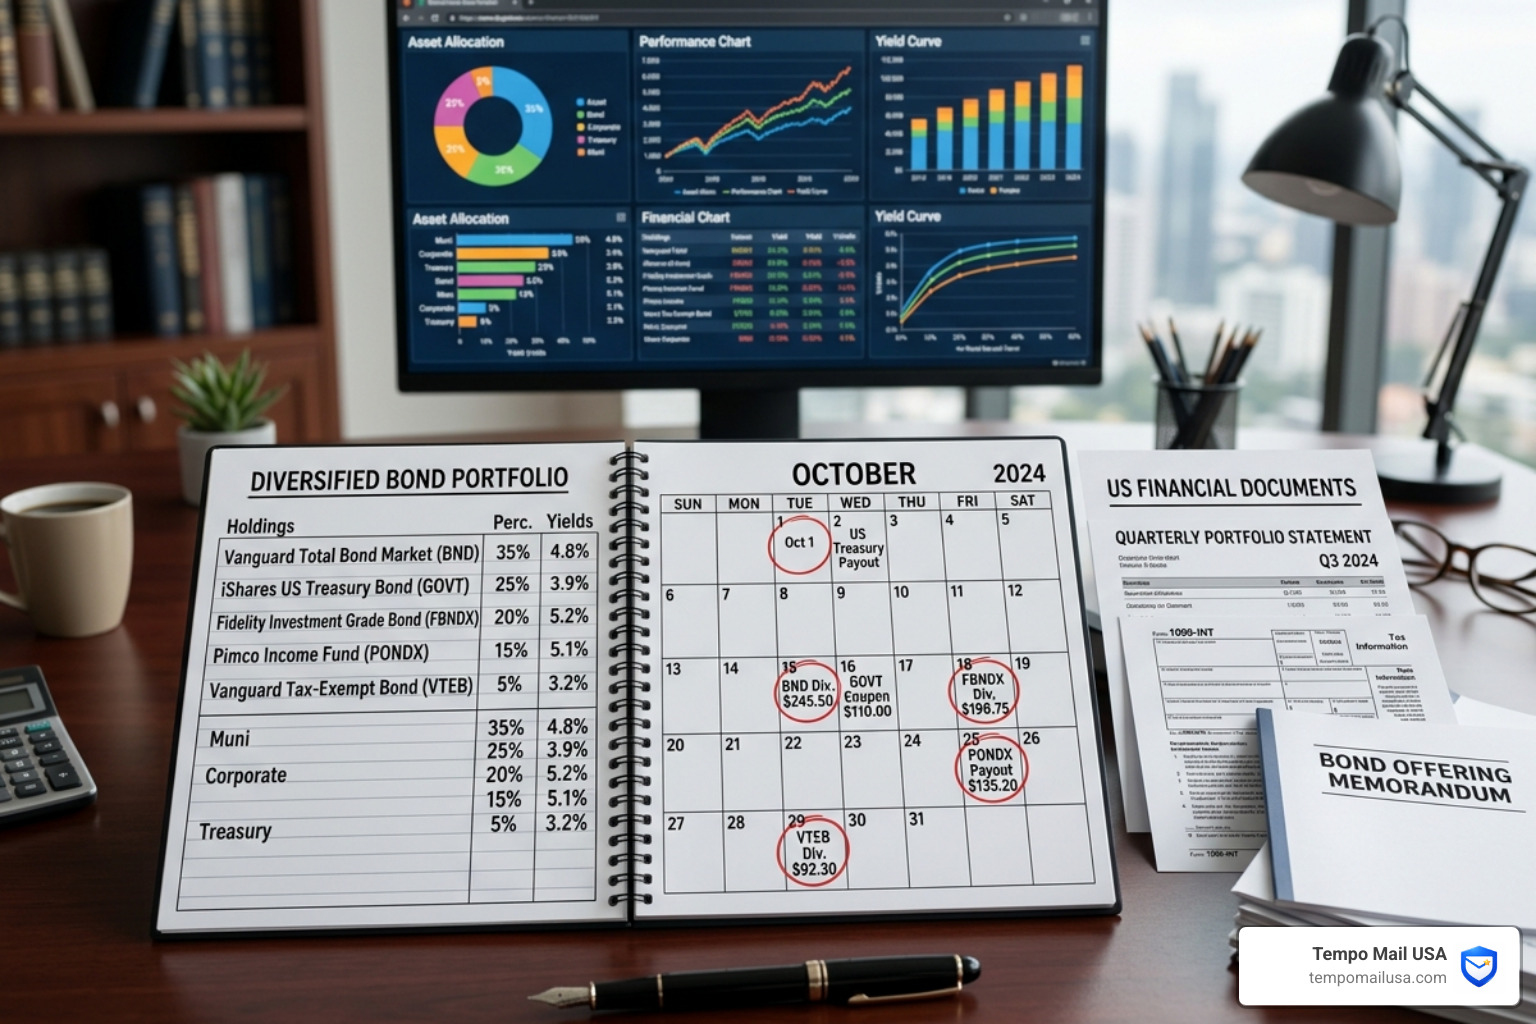

Why Fixed Income Investment Types and Monthly Payout Options Matter More Than Ever
Fixed Income Investment Types and Monthly Payout Options are one of the most searched topics among investors who want predictable, recurring cash flow without the stomach-churning volatility of the stock market. To research these options safely, many investors use Tempo Mail USA to protect their primary email from spam and data leaks when signing up for financial newsletters and brokerage tools.
Here is a quick-reference breakdown of the most common fixed income investment types and whether they offer monthly payouts:
| Investment Type | Monthly Payout Available? | Typical Yield Range |
|---|---|---|
| Corporate Bonds | Some (varies by issuer) | 3% - 7%+ |
| U.S. Treasury Bonds/Notes | No (semiannual) | 4% - 5% |
| Municipal Bonds (e.g., VTEAX) | Some funds pay monthly | ~3.6% (tax-exempt) |
| Certificates of Deposit (CDs) | Rarely | 3% - 5% |
| GICs (Guaranteed Investment Certs) | Depends on terms | 3% - 5% |
| Bond ETFs (e.g., BNDW, VCPIX) | Most pay monthly | 4.7% - 5.2% |
| T-Bill ETFs (e.g., CLIP) | Monthly | ~4.1% |
| Emerging Market Bond ETFs (PCY) | Monthly | ~7.2% |
| REITs | Many pay monthly | Varies (90% dist. rule) |
| Money Market Instruments | Monthly or at maturity | 4% - 5% |
Most people investing for monthly income face the same core problem: many traditional investments pay quarterly or semiannually, but your bills arrive every single month.
That mismatch is exactly why understanding which fixed income vehicles actually deliver monthly cash flow, and which ones just look like they do, is so critical in 2026.
Whether you are a retiree looking to replace a paycheck, a conservative investor building a portfolio cushion, or someone simply tired of watching equity markets swing wildly, fixed income investments offer a proven path to stable, recurring income with lower risk.
This guide breaks down every major fixed income investment type, highlights which ones pay monthly, and shows you how to build a portfolio designed around consistent cash flow.
Understanding Fixed Income Investment Types and Monthly Payout Options

At its heart, a fixed-income security is a debt instrument. When we invest in one, we are essentially acting as the bank, lending our capital to a government, a municipality, or a corporation. In exchange for this loan, the issuer promises to pay us regular interest—known as "coupon payments"—and return our original principal when the investment reaches its maturity date.
Many investors in 2026 now rely on secure platforms, insurance coverage, and advanced privacy tools to avoid financial or data-related risks when managing their wealth. As we navigate a digital-first financial world, protecting your personal information is just as important as protecting your capital. Using services like Tempo Mail USA can act as a PII firewall, ensuring that when you sign up for financial newsletters or research tools, your real identity remains shielded from potential data breaches.
For a deeper dive into the mechanics of these assets, this Guide to Fixed Income: Types and How to Invest explains how these securities provide a "guaranteed" return in the form of interest, provided the issuer remains solvent.
Fixed Income Investment Types and Monthly Payout Options for Bonds and ETFs
While individual bonds often pay interest semiannually, Bond ETFs (Exchange-Traded Funds) are the "secret weapon" for monthly income. Because these funds hold thousands of different bonds that all pay interest at different times, the fund can smooth out these payments and distribute them to you every single month.
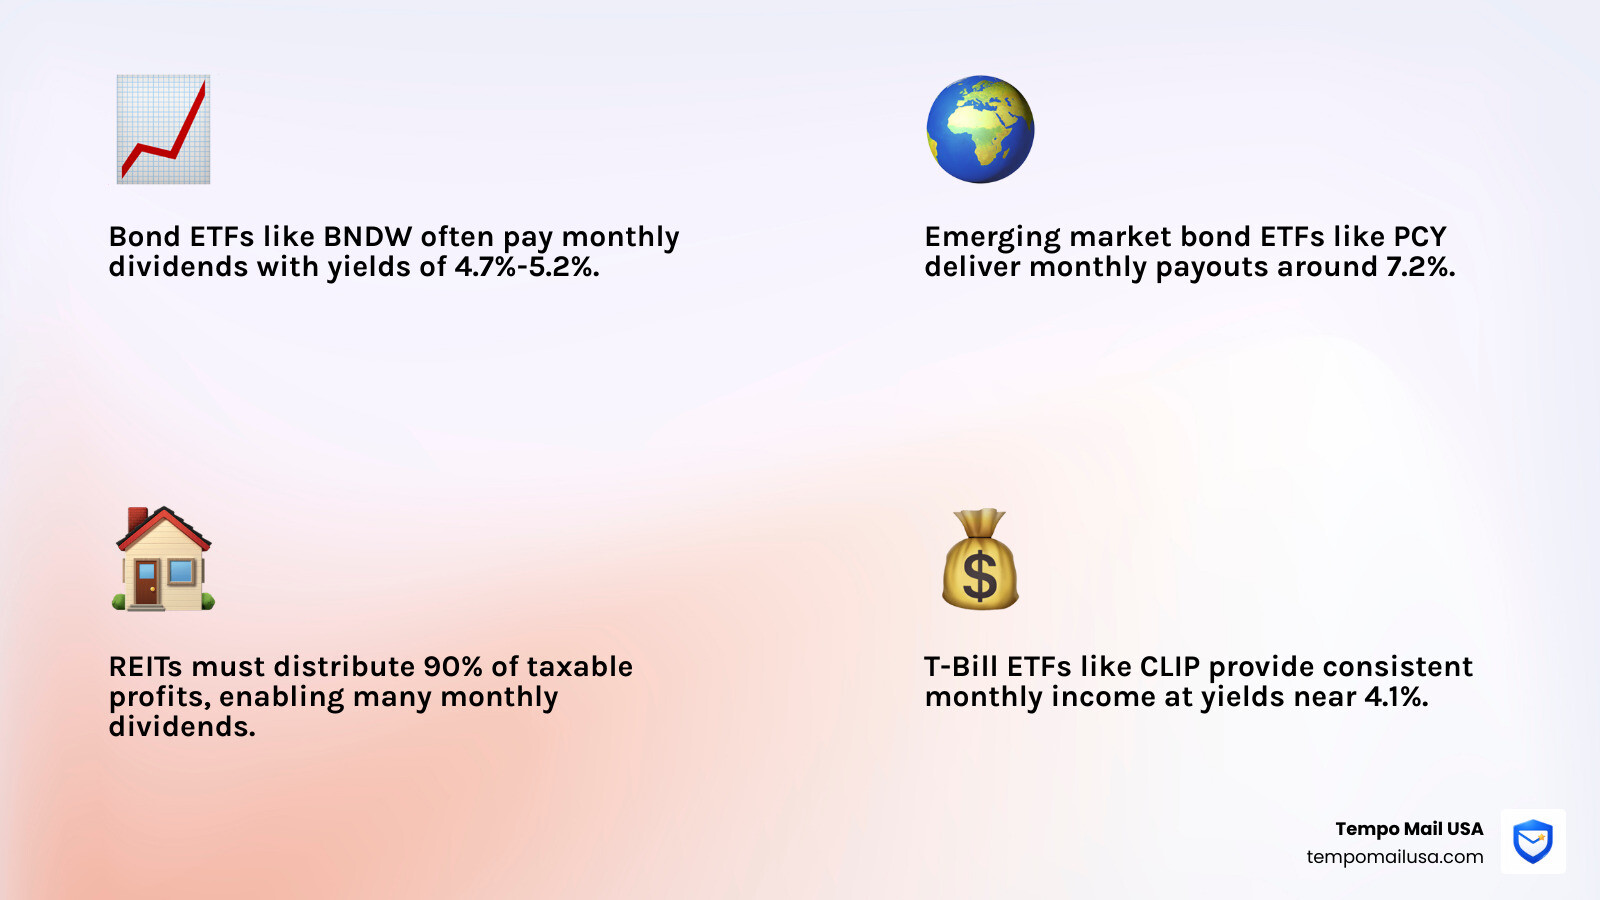
- Vanguard Total World Bond ETF (BNDW): This is a powerhouse for global diversification. It offers a 4.7% yield to maturity by tracking over 27,000 international bonds.
- Invesco Emerging Markets Sovereign Debt ETF (PCY): For those seeking higher yields, PCY delivers approximately 7.2%. It invests in government bonds from emerging nations, offering a monthly payout that packs a punch, though it comes with higher credit risk.
- Vanguard Core-Plus Bond Fund (VCPIX): This "plus" strategy includes high-yield bonds to boost returns, currently offering a 5.2% yield to maturity.
Exploring these 5 Types of Fixed-Income Investments can help you decide if you prefer the safety of government-backed debt or the higher potential of corporate "junk" bonds.
Real Estate Investment Trusts (REITs) and Monthly Dividends
REITs are a unique hybrid. While technically equities, they function much like fixed income because of the 90% distribution rule. By law, REITs must distribute at least 90% of their taxable profits to shareholders as dividends. Because many REITs manage properties with monthly rent rolls (like apartment complexes or retail centers), they are among the most reliable sources of monthly dividends in the marketplace.
Top Assets for Consistent Monthly Cash Flow
If your goal is absolute consistency, you need to look at short-term instruments. These assets prioritize liquidity and safety, ensuring that your "mailbox money" arrives without fail.
- Certificates of Deposit (CDs): These are FDIC-insured up to $250,000, making them incredibly safe. While most pay at maturity, some "income CDs" allow for monthly interest transfers to a linked savings account.
- Money Market Instruments: These are very short-term debt obligations. They are the closest thing to cash while still earning a competitive rate.
- Global X 1-3 Month T-Bill ETF (CLIP): This is a standout for 2026. With a 4.1% yield and a tiny 0.1-year duration, it carries almost zero interest rate risk. It’s a great place to park cash while waiting for better opportunities.
As noted in this Fixed-Income Security Definition, Types, and Examples, the predictability of these assets is what makes them the bedrock of a conservative portfolio.
Fixed Income Investment Types and Monthly Payout Options for Conservative Portfolios
For our most conservative friends, Guaranteed Investment Certificates (GICs) and government-backed treasuries are the gold standard. GICs offer a fixed rate of return for a set period, often ranging from 30 days to 10 years. They are virtually risk-free, providing a "safety first" approach to wealth preservation.
Tax-Advantaged Monthly Income Strategies
If you are in a high tax bracket, what you keep matters more than what you earn.
- Municipal Bonds: These are issued by states or cities to fund public works like schools and highways. The interest is generally exempt from federal income tax.
- Vanguard Tax-Exempt Bond Index Fund (VTEAX): This fund provides a 3.6% yield to maturity that is exempt from federal income tax and the Alternative Minimum Tax (AMT). For someone in the 37% tax bracket, that 3.6% "tax-free" yield is equivalent to earning nearly 5.7% on a taxable bond!
The Hidden Risks: Protecting Your Capital in 2026
No investment is truly "risk-free." Even the safest bond has enemies. In 2026, we must be vigilant about four specific threats:
- Interest Rate Risk: When market interest rates rise, existing bond prices fall. This is because new bonds are being issued with higher coupons, making your "old" bond less attractive.
- Credit Risk: This is the danger that the issuer (the company or city) won't be able to make their payments.
- Inflation Erosion: If your bond pays 4% but inflation is 5%, you are technically losing purchasing power every year.
- Liquidity Risk: Some individual bonds are hard to sell quickly without taking a price hit.
To stay safe, many experts suggest using advanced privacy protection when accessing your brokerage accounts, especially when using public Wi-Fi, to prevent hackers from intercepting your financial data.
Credit Ratings and Default Protection
We highly recommend checking credit ratings from agencies like Moody’s or S&P before buying any individual bond. "Investment-grade" bonds (rated BBB-/Baa3 or higher) are generally safe, while "Speculative" or "Junk" bonds offer higher yields to compensate for a much higher chance of default.
Inflation and Real Rate of Return
To fight inflation, consider TIPS (Treasury Inflation-Protected Securities). The principal of a TIPS bond increases with inflation (measured by the CPI). While the interest rate is fixed, it is applied to the adjusted principal, meaning your payout grows as prices at the grocery store rise.
Strategic Portfolio Construction: The Bond Laddering Method
One of the smartest ways to manage Fixed Income Investment Types and Monthly Payout Options is through a "Bond Ladder." Instead of buying one big bond that matures in 10 years, you buy several smaller bonds that mature in staggered intervals (e.g., 1 year, 2 years, 3 years, etc.).
| Strategy | Individual Bonds | Bond ETFs/Funds |
|---|---|---|
| Control | High (You pick the issuer) | Low (Manager picks) |
| Fees | $1 - $2 per bond | 0.05% - 0.50% expense ratio |
| Liquidity | Can be low | High (Sell anytime) |
| Maturity | Fixed date | No fixed maturity |
| Diversification | Hard for small investors | Instant (Thousands of bonds) |
As one bond matures, you take that cash and reinvest it at the "top" of the ladder. This helps you capture rising interest rates while maintaining a steady flow of cash. To see how much you need to invest to hit your monthly goals, you can calculate your potential returns using our specialized tools.
Building a Monthly Income Stream
A bond ladder provides a predictable schedule of maturing principal, which can be used for living expenses or reinvested. In 2026, many digital brokers offer "laddering tools" that automate this process for you, making it easier than ever to maintain a monthly income stream.
Choosing Between Individual Bonds and ETFs
For most of us, Bond ETFs are the superior choice. They offer instant diversification and professional management for a very low fee (often as low as 0.05% for Vanguard funds). Individual bonds require more capital—often $1,000 to $5,000 minimum per bond—and can be much harder to trade on the secondary market.
Fixed Income vs. Equities: How to Choose the Right Option
Why choose fixed income over stocks? It comes down to the "Priority of Payout." In the unfortunate event of a corporate bankruptcy, bondholders are legal creditors. They get paid before preferred stockholders, and long before common stockholders (who usually get nothing).
Cost vs. Value Breakdown
When buying fixed income, watch the "Bid-Ask Spread." This is the difference between what a seller wants and what a buyer offers. In the bond world, commissions are often "baked into" the price you see on your screen. Always look at the Net Yield—the actual return you get after all fees are subtracted.
Who Should Prioritize Fixed Income?
- Retirees: Those who need to replace their salary with a "pension-like" monthly check.
- Conservative Investors: People who have already "won the game" and want to preserve their wealth rather than risk it for more growth.
- The "Safety Sleeve": Even aggressive investors should keep 10-20% in fixed income to act as a "ballast" during stock market crashes.
Frequently Asked Questions about Fixed Income
Which fixed income investments pay monthly?
Bond ETFs, REITs, and Money Market funds are the primary investments offering monthly payouts. While individual bonds typically pay semiannually, these funds aggregate various interest-bearing assets to provide a consistent monthly cash flow to investors.
How does interest rate risk affect my monthly payouts?
Interest rate risk primarily impacts the market value of the investment rather than the fixed monthly payout. However, for Bond ETFs, the distribution amount may vary slightly over time as the fund manager reinvests in new bonds at prevailing market rates.
Are monthly payout bond ETFs safer than individual bonds?
Bond ETFs are generally safer regarding diversification because they hold thousands of securities, minimizing the impact of a single issuer's default. Individual bonds offer more certainty for principal return at maturity, but carry higher concentrated risk if the issuer fails.
Conclusion
Achieving financial independence in 2026 requires a balanced approach. By mastering Fixed Income Investment Types and Monthly Payout Options, you create a solid foundation for your portfolio that works for you even while you sleep.
As you build your wealth, your digital footprint is an asset that needs protection. At Tempo Mail USA, we provide the ultimate PII firewall. Our secure alias generation allows you to interact with financial platforms, brokers, and research sites without exposing your real identity to the "wild west" of the internet.
Shield your identity while you grow your income. For more tips on protecting your financial life and to calculate your potential returns, visit our tools section today. Your future self—and your inbox—will thank you.