


Why So Many E-Bike Buyers Regret How They Paid
Electric Bike Financing Options USA is one of the most searched topics among new e-bike buyers — and for good reason. With quality e-bikes ranging from around $1,000 to $3,000+, very few people want to drop that full amount upfront. If you are ready to buy, many top-tier retailers are currently offering exclusive 0% APR seasonal promotions that can save you over $500 in interest costs if you lock in your rate this month.
The good news: there are several solid financing paths available right now. Here's a quick breakdown of the most common options:
Top E-Bike Financing Options in the USA (April 2026):
| Provider | APR Range | Terms Available | Credit Score Impact |
|---|---|---|---|
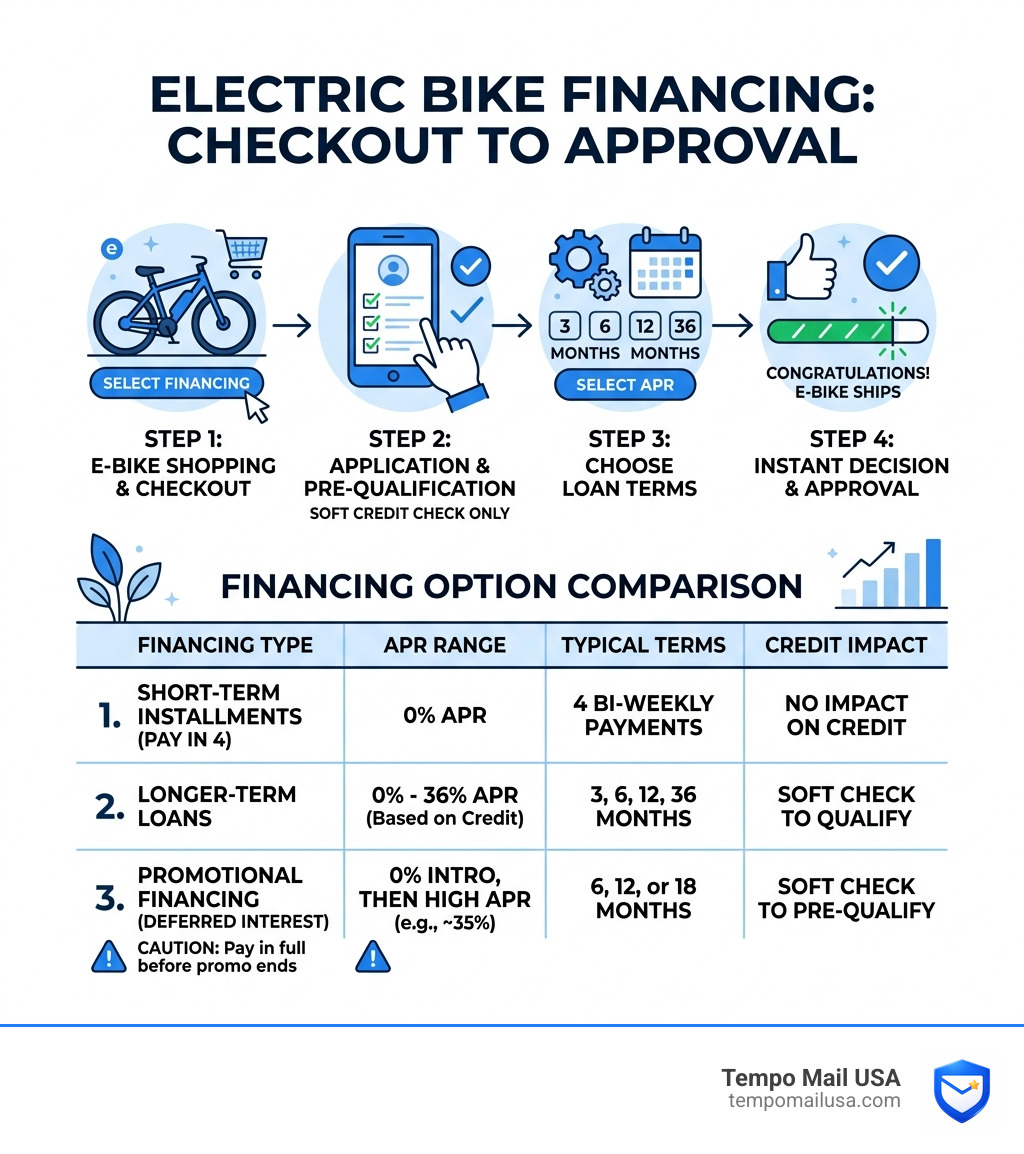
| Affirm | 0% - 36% | 3, 6, 12, 36 months | Soft check only to check rates |
| Shop Pay Installments | 0% - 36% | 4 bi-weekly or 3/6/12 months | No impact for Pay in 4 |
| Klarna | 0% (Pay in 4) or variable | 4 payments or up to 36 months | No hard pull for Pay in 4 |
| Synchrony | 0% promo, then 34.99% | 6, 12, or 18 months | Soft check to prequalify |
| Bread Pay (Comenity Capital Bank) | Varies | Monthly plans | Soft check for rate check |
The bad news: most buyers jump straight to the checkout financing button without understanding the terms — and some end up paying hundreds more than they expected, or worse, damaging their credit.
Financing an e-bike is genuinely a smart move when done right. Monthly payments starting around $39/month on a $1,299 bike make ownership accessible without draining your savings. But there are real traps buried in the fine print — deferred interest clauses, penalty APRs pushing nearly 40%, and data privacy risks most shoppers never think about.
This article walks through the 7 most costly mistakes e-bike buyers make when financing — so you don't have to learn them the hard way.
1. Falling for the "Deferred Interest" Trap in Electric Bike Financing Options USA
One of the most dangerous mistakes we see is confusing "0% APR" with "Deferred Interest." While they sound similar, the financial consequences of a mistake here are massive. Many popular retailers offer promotional periods through partners like Synchrony Bank, promising no interest if paid in full within 6, 12, or 18 months.
However, if you have even $1 remaining on your balance when that promotional period ends, the lender doesn't just start charging interest then. They back-calculate the interest on the entire original purchase amount from day one. With a standard purchase APR often sitting at 34.99%, a "free" loan can suddenly become an expensive nightmare.
How Promotional Terms Can Backfire
Most people assume that making the "minimum payment" suggested on their statement will clear the debt in time. This is a myth. Minimum payments are often calculated to keep you in debt longer. To truly benefit from Bike Financing: Electric Bikes, MTB, Road & More – Mike's Bikes, you must manually divide your total balance by the number of promotional months and pay that specific amount.
If you aren't sure how much interest you might be risking, using an Interest Rate Calculator can help you visualize the potential damage of missing that payoff window.
The Reality of 0% APR vs. Deferred Interest
True 0% APR, often found through providers listed at Financing – Electric Bikes of America, simply means no interest is charged during the term. Deferred interest is a gamble. Furthermore, if you are late on a single payment, some lenders trigger a "Penalty APR" which can skyrocket to 39.99%. We recommend using a Credit Card Payoff Calculator to compare how these high rates stack up against a standard credit card—you might be surprised to find your Visa is actually cheaper than a botched promotional loan.
2. Underestimating the Long-Term Cost of High APR Loans
When you see a "starting at $39/month" sticker, it is easy to forget the total math. Depending on your credit score, Electric Bike Financing Options USA can range from 0% all the way to 36% APR. Over a 36-month term, that interest adds up to a significant portion of the bike's value.
| Loan Amount | APR | Term | Monthly Payment | Total Interest Paid | Total Cost |
|---|---|---|---|---|---|
| $2,000 | 0% | 12 Months | $166.67 | $0 | $2,000 |
| $2,000 | 15% | 24 Months | $97.00 | $328 | $2,328 |
| $2,000 | 36% | 36 Months | $91.33 | $1,288 | $3,288 |
As shown above, a high APR can result in you paying for one and a half bikes by the time the loan is finished. We always suggest running your numbers through a Personal Loan Calculator before hitting "Confirm" at checkout.
Real-World Monthly Payment Examples for Electric Bike Financing Options USA
Let's look at some current market examples from April 2026. A $1,299 e-bike purchase might cost you roughly $39/mo over 36 months if you qualify for a 15% APR. If you can snag a 0% APR deal for 3 months, that same bike would cost $433/mo. You can find more specific breakdowns of these plans at Ride Now, Pay Later | E-Bikes Financing Options - Life EV.
Why a $1,995 Bike Can Cost You $2,500
The "hidden" cost is almost always the term length. Stretching a $1,995 purchase over 36 months at a 15% APR results in a total payment of roughly $2,480. While the $69/mo payment feels affordable, you are losing nearly $500 in purchasing power. If you find yourself stuck in a high-interest loan, checking a Refinance Calculator might help you find a way to move that debt to a lower-interest personal loan later on.
3. Exposing Your PII During Online Financing Applications
In the rush to secure a new ride, many users overlook the digital risks. Financing applications require your most sensitive Personally Identifiable Information (PII): Social Security Number, date of birth, mobile number, and annual income. Most users today rely on secure platforms, insurance-backed services, and advanced privacy tools to avoid financial and data risks during this process.
The Risk of Unsecured Checkout Pages
When you apply for financing at a retailer like those mentioned on Easy and Affordable Financing for Electric Bikes | Bandit Bikes, your data is often passed to third-party lenders. If the connection isn't properly encrypted, or if the retailer’s database is compromised, your financial identity is at risk.
We strongly recommend that you Secure your financial data with a VPN before starting any credit application. A VPN ensures that your data is encrypted from the moment it leaves your device, preventing "man-in-the-middle" attacks on public or unsecured Wi-Fi.
Protecting Your Identity with Secure Electric Bike Financing Options USA
Beyond a VPN, you should be wary of how many "newsletters" and "marketing lists" you end up on after a credit check. This is where a PII firewall becomes essential. When a site asks for an email address to "check your rate," they are often building a profile on you.
Using Tempo Mail USA allows you to provide a temporary, secure email alias. This shields your real identity from data brokers and ensures that if the lender's marketing partner suffers a data leak, your primary inbox remains safe. You can check your eligibility at Financing using these privacy-first habits to keep your credit profile clean and your data private.
4. Decision Guide: Choosing Between Affirm, Klarna, and Shop Pay
Not all Buy Now, Pay Later (BNPL) services are created equal. Use this comparison to decide which provider fits your financial situation:
- Affirm: Best for long-term financing (up to 36 months). They are very transparent about total costs and generally don't charge late fees, though interest can be high if your credit isn't perfect.
- Shop Pay Installments: Excellent for smaller purchases ($50–$999). Their "Pay in 4" option is interest-free and doesn't affect your credit score. For larger purchases up to $17,500, they offer monthly plans.
- Klarna: Offers the most flexibility, including a "Pay in 30 days" option which lets you try the bike before the first payment is even due.
When deciding between these, consider using a Student Loan Repayment Calculator to see how an extra monthly payment fits into your existing debt obligations.
Comparing Buy Now Pay Later (BNPL) Features
If you are looking at a higher-end e-bike that costs as much as a used car, you might even compare these rates against a House Loan Calculator or a small home equity line of credit, which sometimes offers lower APRs than retail BNPL providers.
Which Option Actually Saves You the Most Money?
The "winner" is always the 0% APR option that you can pay off early. Most BNPL providers, including Bread Pay and Affirm, do not charge prepayment penalties. If you get a tax refund or a bonus, paying off your $2,000 e-bike early can save you hundreds in projected interest. Use a Home Loan Calculator to see how "extra payments" on any loan—even an e-bike loan—drastically reduce the total interest you pay.
5. Neglecting the ROI of E-Bikes vs. Car Ownership
One mistake people make is looking at e-bike financing as an "extra" expense rather than a "replacement" expense. If financing an e-bike allows you to sell a second car or stop paying for a monthly parking pass, the bike pays for itself almost immediately.
Cost Breakdown: E-Bike vs. Commuter Vehicle
According to data from Ride Now, Pay Later | E-Bikes Financing Options - Life EV, the average commuter spends $150/month on gas and $500/year on basic maintenance. An e-bike costs virtually $0 in fuel and less than $100 a year to maintain.
If your e-bike payment is $69/month, but you save $150/month on gas, you are actually making $81 a month by financing the bike. You can Calculate your potential savings here to see your personal Return on Investment.
Building Credit Through Responsible Financing
Unlike a credit card, which can hurt your score if you carry a high balance (utilization), some e-bike loans are reported as "installment loans." Making on-time payments on an installment loan is one of the best ways to build a healthy credit mix. However, always verify if the provider reports to the major bureaus. You can track your progress and plan your next financial move with a Personal Loan Calculator.
The Ultimate E-Bike Financing Checklist
Before you sign any digital contracts, run through this checklist to ensure you aren't making a mistake:
- Check for Soft Pull: Confirm the lender uses a soft credit check to prequalify you so your score isn't dinged just for looking.
- Verify 0% APR vs. Deferred Interest: If it's deferred, set an alarm for one month before the promo ends to ensure it's paid in full.
- Calculate Total Cost: Use a calculator to see the total price including interest, not just the monthly payment.
- Protect Your PII: Use a VPN and a temporary email from Tempo Mail USA to prevent identity theft and spam.
- Review Early Payoff Terms: Ensure there are no penalties for paying the loan off early.
- Check State Availability: Some providers like Klarna have restrictions in states like West Virginia or New Mexico.
Frequently Asked Questions about E-Bike Financing
Does checking my eligibility for e-bike financing affect my credit score?
No. Most providers like Affirm and Bread Pay use a soft credit pull for eligibility checks, which has zero impact on your credit score. A hard inquiry only occurs if you finalize and accept the loan terms.
Is 0% APR financing actually interest-free?
Yes, as long as the balance is paid in full within the promotional period. However, if the plan uses "Deferred Interest," failing to pay the full amount by the deadline results in interest being charged retroactively from the purchase date at rates up to 34.99%.
What is the safest way to apply for e-bike financing online?
The safest method is to use a VPN to encrypt your connection and a service like Tempo Mail USA to create a PII firewall. This protects your Social Security Number and personal data from being intercepted or sold to third-party marketing lists.
Conclusion
Navigating Electric Bike Financing Options USA in April 2026 requires a balance of financial savvy and digital caution. By avoiding high-interest traps and protecting your personal data, you can enjoy the benefits of e-mobility without compromising your financial future.
Financing is a powerful tool that puts premium, high-quality e-bikes within reach for almost anyone. However, the "convenience" of a checkout button should never override your duty to protect your identity. To further shield your identity during online signups and financing applications, using a service like Tempo Mail USA acts as a critical PII firewall. It ensures your primary email and personal information remain secure from data brokers and potential leaks, letting you focus on the road ahead rather than your credit report.