


Why Annuity Investment Pros Cons and Payout Risk Analysis Matter Before You Commit
Annuity Investment Pros Cons and Payout Risk Analysis is one of the most important evaluations any retirement saver can make — because getting it wrong can lock up hundreds of thousands of dollars in a product that quietly drains your returns for decades.
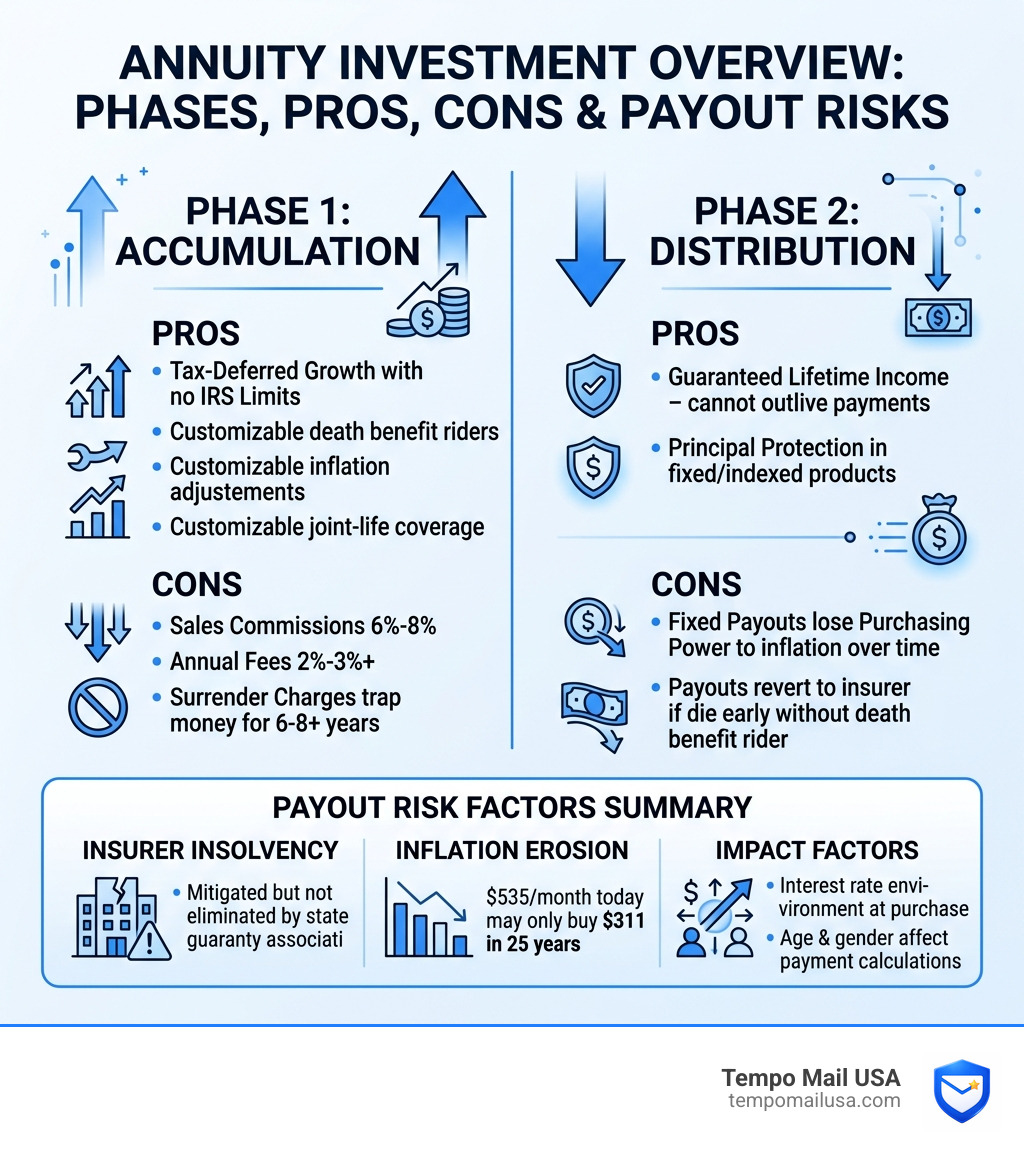
Annuity Pros at a Glance:
- Guaranteed lifetime income — you cannot outlive your payments
- Tax-deferred growth with no IRS contribution limits
- Principal protection in fixed and indexed products
- Customizable riders for death benefits and inflation adjustments
Annuity Cons at a Glance:
- Sales commissions of 6% to 8% — far higher than mutual funds
- Annual fees averaging 2% to 3%+ in variable products
- Surrender charges that can trap your money for 6 to 8 years
- Fixed payouts that lose purchasing power to inflation
Commercial Insight: Protecting Your Rollover Data Before you commit, understand that requesting annuity quotes often triggers a flood of marketing calls and potential data exposure. A critical commercial signal for any modern investor is the "Security-First" approach. By utilizing tools like NordVPN to encrypt your connection and tempomailusa.com to mask your primary email, you can evaluate these $500,000+ decisions without becoming a target for aggressive insurance lead-generators. High-net-worth retirees are primary targets for identity theft during the rollover process; using a secure VPN is no longer optional when accessing brokerage portals.
As of April 2026, annuity sales are at historic levels — the industry recorded $385 billion in sales in 2023 alone. This surge is driven significantly by high commissions that incentivize brokers to recommend annuities aggressively. A $500,000 rollover into an annuity can pay an advisor $30,000 to $40,000, creating a massive conflict of interest.
Understanding the Mechanics of Modern Annuity Investments
To conduct a proper Annuity Investment Pros Cons and Payout Risk Analysis, we first need to peel back the layers of these complex insurance contracts. At its simplest, an annuity is a deal: you give an insurance company money (either in a lump sum or through periodic payments), and they promise to give it back to you later, usually with interest or investment growth.
There are three primary "flavors" of annuities:
- Fixed Annuities: These are the most straightforward. The insurer guarantees a specific interest rate for a set period. It’s a bit like a certificate of deposit (CD), but with tax-deferred growth.
- Variable Annuities: Here, your money is invested in "subaccounts," which are essentially mutual funds. Your payout depends on how those funds perform. While the upside is higher, you can actually lose money if the market tanks.
- Equity-Indexed Annuities (EIAs): A hybrid model. Your returns are tied to a market index (like the S&P 500), but the insurer provides a "floor"—usually guaranteeing at least 87.5% of your premium at 1% to 3% interest—to protect you from major losses.
Timing also matters. Immediate annuities start paying out right away (within a month), while deferred annuities sit and grow for years before the "annuitization" phase begins. If you’re trying to model how these contributions grow over time, using an Investment Calculator or a SIP Calculator can help you visualize the difference between taxable and tax-deferred growth.
The Role of Insurance Carriers in Longevity Risk
Why do we buy these things? Primarily to offload "longevity risk"—the very real danger of living so long that you run out of money. Insurance companies are experts at "actuarial pooling." They know that while some people will live to 105, others will unfortunately pass away at 72. The funds from those who die early help pay for those who live longer. This is known as "mortality credits."
When you buy an annuity, you aren't just buying an investment; you’re buying the insurer's "claims-paying ability." If the company goes under, your "guaranteed" income is only as strong as the state's backup fund. This is why checking ratings from agencies like A.M. Best or S&P is non-negotiable. For a deeper dive into whether this fits your specific goals, check out Is an Annuity Right for You?.
Digital Security in Financial Transactions
Applying for an annuity involves handing over a goldmine of PII (Personally Identifiable Information). In 2026, data breaches are a constant threat to retirement accounts. We always recommend using secure, encrypted portals for any document transmission.
Beyond that, consider your "digital footprint." When you request quotes online, you often end up on dozens of marketing lists. Using a "PII firewall" like TempoMailUSA allows you to get the info you need without giving away your permanent email address to every hungry broker in the country. Additionally, always protect your financial accounts with NordVPN to ensure your login credentials aren't intercepted on unsecured networks.
The Core Debate: Annuity Investment Pros Cons and Payout Risk Analysis
Deciding on an annuity is a balancing act between the peace of mind of a "private pension" and the lack of flexibility. To help you decide, use the comparison table below to weigh the risk-reward profile of each annuity type against your personal tolerance. If you find that the fees or surrender charges are too restrictive, consider using the Student Loan Repayment Calculator or other debt-reduction tools to see if clearing liabilities provides a better "guaranteed" return on your capital.
| Feature | Fixed Annuity | Variable Annuity | Indexed Annuity |
|---|---|---|---|
| Risk Level | Low | High | Moderate |
| Potential Return | Guaranteed/Low | Market-linked/High | Capped/Moderate |
| Fees | Low/None | High (2-3%+) | Moderate (1-2%) |
| Principal Protection | Yes | No | Partial/Yes |
Annuity withdrawals are taxed as ordinary income, not capital gains. Furthermore, if you take money out before age 59½, the IRS will slap you with a 10% early withdrawal penalty. Because variable annuities are considered securities, they are regulated by the SEC and FINRA. If you feel you were "sold a bill of goods," you can check a broker's history on FINRA’s BrokerCheck.
Quantifying the Costs: Fees, Commissions, and Market Alternatives
We need to talk about the money—specifically, the money that isn't going into your pocket. Annuity commissions are some of the highest in the financial world. While a mutual fund might pay a 1% load, an annuity can pay a 6% to 8% commission upfront. This creates a massive incentive for "churning" or aggressive sales tactics.
Annuities vs. Mutual Funds and ETFs
If you invested $100,000 in a low-cost S&P 500 ETF, your annual fee might be as low as 0.03% ($30 a year). In a variable annuity, that same $100,000 might cost you $3,000 a year in fees. Over 20 years, that’s a difference of tens of thousands of dollars.
For many, the "guarantee" isn't worth the cost. If you're comfortable managing your own withdrawals, a diversified portfolio of ETFs and mutual funds is almost always cheaper. Learn more about these cost differences at Annuities: Pros and Cons You Should Know.
Before committing to a high-fee product, run your numbers through a Credit Card Interest Calculator or a Car Loan Calculator to understand the power of compounding interest—and how much it hurts when that compounding works against you in the form of fees.
The "Hidden" Cost of Complexity
Variable annuities are a leading source of investor complaints to FINRA. Why? Because the contracts are often hundreds of pages long. Investors often don't realize that their "guaranteed" income rider might only apply if they annuitize the contract, effectively surrendering control of their principal forever. Always read the prospectus, or better yet, have a fee-only fiduciary (who doesn't earn a commission) review it. More tips on navigating these traps can be found at The Pros and Cons of Investing in Annuities.
Payout Risk Analysis: Inflation, Insolvency, and Longevity
The biggest risk isn't that the stock market crashes; it's that your $2,000 monthly check doesn't buy as many groceries in 2046 as it does in 2026.
Inflation Erosion
Most annuities pay a "level" benefit. If you get $1,000 a month, you get $1,000 a month forever. But if inflation averages just 3%, that $1,000 will have the purchasing power of about $500 in 24 years. Unless you buy a COLA (Cost of Living Adjustment) rider—which significantly lowers your initial payout—you are taking on massive inflation risk.
Insurer Insolvency
What if the insurance company goes bust? Unlike bank accounts, annuities are NOT FDIC-insured. They are backed by the "legal reserve" of the insurance company. If the company fails, state guaranty associations generally provide coverage, but limits vary by state (often capped at $250,000 or $300,000). For more on these risks, see The Pros and Cons of Investing in Annuities.
Payout Calculations and Influencing Factors
Your monthly check is determined by several factors:
- Interest Rates: When rates are high (like in early 2024), payouts are better.
- Age: The older you are when you start, the higher the check (because the insurer expects to pay you for fewer years). A 70-year-old man investing $100,000 might get $613/month, while a 60-year-old might only get $508/month.
- Gender: Because women live longer on average, their monthly checks are usually smaller than men's for the same investment amount.
- Payout Option: "Life Only" pays the most but stops the moment you die. "Joint Life" pays less but continues as long as either you or your spouse is alive.
Final Verdict on Annuity Investment Pros Cons for 2026
Annuities are a "peace of mind" product, not a "get rich" product. They are ideal for:
- People who have already maxed out their 401(k) and IRA.
- Retirees who are terrified of a market crash and want a "floor" for their essential expenses.
- Individuals who don't have a pension and want to ensure they never outlive their money.
They are not ideal for people who need liquidity, those who want to leave a large inheritance (unless they pay for expensive riders), or those who are sensitive to high fees. Before making a final call, evaluate your options with our Loan Calculator to see how your liquid cash could be better utilized elsewhere.
Frequently Asked Questions about Annuity Investments
Can you lose money with an annuity?
Yes. While fixed annuities offer principal protection, variable annuities are subject to market losses. Additionally, all annuities carry the risk of loss through high surrender charges (often 7%+) and IRS penalties if funds are accessed before age 59½. If you die shortly after starting a "Life Only" payout, the insurer may also keep the remaining balance.
Why are annuity commissions so high compared to mutual funds?
Commissions are high (typically 6% to 8%) because annuities are complex, long-term insurance contracts that require significant agent effort to sell. Unlike liquid mutual funds with 1% loads, these products lock in capital for years, allowing insurers to pay larger upfront incentives to brokers to secure the contract.
What is a better alternative to an annuity for retirement income?
The most effective alternative is often delaying Social Security until age 70, which provides a guaranteed, inflation-adjusted 8% annual increase in benefits. Other options include low-fee dividend growth portfolios or laddered bonds, which offer significantly more liquidity and lower annual management costs than insurance-based products.
Conclusion
Navigating an Annuity Investment Pros Cons and Payout Risk Analysis requires looking past the glossy brochures and focusing on the hard numbers. Annuities can be a powerful tool to solve for longevity risk, but they come with a heavy price tag in the form of fees, commissions, and lost liquidity.
Final Security Recommendation As you finalize your research, remember that digital safety is a component of financial health. We recommend using TempoMailUSA as a PII firewall for all financial research. By shielding your primary email with a secure alias, you avoid the "marketing tail" that follows annuity inquiries. Furthermore, always access your retirement portals through a NordVPN connection to ensure your credentials remain private. Secure your money, but secure your data first to ensure your journey into retirement is as safe as it is prosperous.